Global Ferronickel Holdings Inc. (FNI) reported a 50.9-percent increase in consolidated net income to P2.29 billion in the first nine months of 2026, driven by higher nickel ore prices, increased shipment volumes and favorable foreign exchange movements.
The nickel ore producer said Thursday that net income for the nine months ended September 30 rose from P1.52 billion in the same period last year.
Consolidated revenues increased 36.9 percent to P9.15 billion from P6.68 billion, while income before income tax climbed 48.5 percent to P2.93 billion.
The company attributed the improvement to stronger nickel ore prices, higher shipment volumes, an 87.5-percent increase in its share of net income from associates and a 59.1-percent reduction in finance costs.
Earnings per share also increased 51 percent to P0.4498 from P0.2978 a year earlier.
FNI President Dante R. Bravo said the results reflected improved operating performance and continued operational efficiencies.
"We are encouraged by the Group's performance in the first nine months of the year, supported by higher shipment volumes, improved nickel ore prices, and continued operational efficiencies," Bravo said.
He added that the company would focus on strengthening its operating capabilities, managing costs and maintaining efficient operations to sustain its performance.
Higher shipments and nickel prices
FNI completed 73 nickel ore shipments during the nine-month period, up from 66 shipments in the same period last year.
Total shipment volume reached 3.994 million wet metric tons (WMT), a 9-percent increase from 3.664 million WMT in 2025.
The average realized nickel ore selling price rose 16.9 percent to US$37.39 per WMT from US$31.99 per WMT.
Prices for low-grade ore increased 15.3 percent to US$34.44 per WMT, while medium-grade ore prices climbed 17.3 percent to US$49.85 per WMT.
The company said the higher proportion of medium-grade ore in its sales mix also contributed to the increase in its overall average selling price.
Nickel ore prices strengthened during the first half of 2026 amid robust demand from China and Indonesia, alongside tighter supply conditions in Indonesia following the implementation of production quota restrictions.
Prices moderated in the third quarter as supply constraints eased and market demand softened. However, average realized selling prices for the nine-month period remained above 2025 levels.
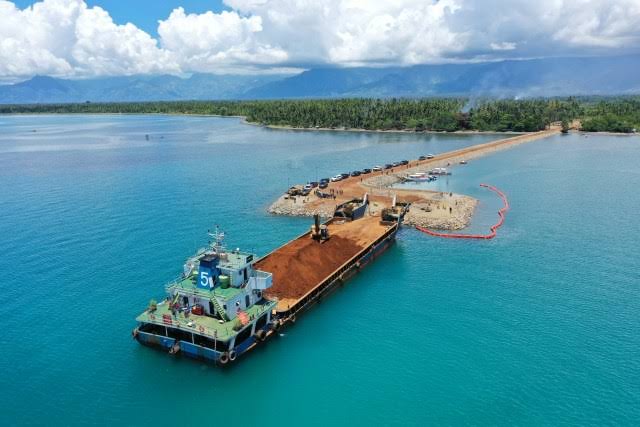
Mining operations accounted for approximately 99.9 percent of FNI's consolidated revenues, with the remaining 0.1 percent generated by services provided by Mariveles Harbor Corp.
The company also benefited from a higher average peso-to-dollar exchange rate of P61.21, compared with P56.94 in the previous year. The favorable movement increased the peso value of its dollar-denominated nickel ore export revenues.
Mining remains core business
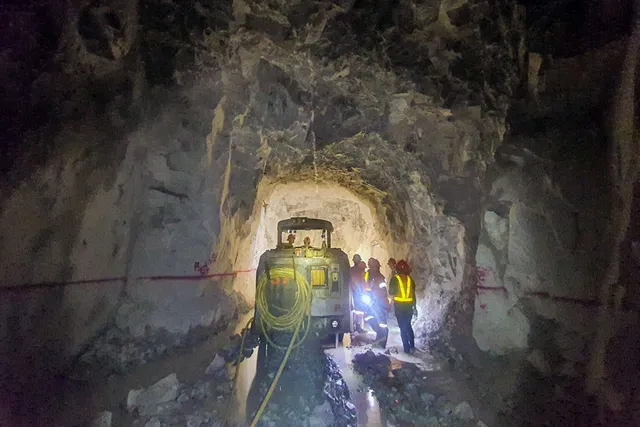
FNI is a holding company whose principal subsidiary is Platinum Group Metals Corp. (PGMC), the country's second-largest nickel ore producer.
PGMC's mining assets cover 5,219 hectares in Cagdianao, Surigao del Norte, and 2,835 hectares in Brooke's Point, Palawan.
The group is pursuing a diversification strategy that includes investments in steel production and port operations, alongside its existing nickel mining business.
FNI said higher contributions from associates, lower finance costs and favorable foreign exchange movements complemented stronger mining revenues in the first nine months of 2026.