DMCI Holdings Inc. reported a 28% increase in consolidated net income for the first nine months of 2026, reaching P15 billion from P11.7 billion a year earlier, driven by record earnings from its nickel mining and power generation businesses and an improving cement segment.
The diversified conglomerate said all its subsidiaries delivered improved earnings contributions, supported by stronger electricity prices, higher mining production and shipments, improved real estate performance and lower cement losses.
Third-quarter net income rose 33% to P3.6 billion from July to September, with stronger contributions from power generation, nickel mining and real estate, alongside continued improvements in cement operations.
Combined contributions from the group's on-grid and off-grid power businesses increased 42% to P5.9 billion from P4.2 billion, with both segments recording their highest nine-month earnings to date.
Semirara Mining and Power Corp. (SMPC) remained the group's largest earnings contributor, accounting for P6.3 billion, up 8% from P5.8 billion in the same period last year.
Its power business generated P4.8 billion, a 51% increase from P3.2 billion, supported by higher spot electricity prices and improved plant performance.
However, coal contributions declined 46% to P1.5 billion from P2.8 billion amid lower shipments and challenging mining conditions.
DMCI Homes contributed P3.1 billion, up 21% from P2.6 billion, as lower revenue reversals from cancellations, a higher-value project mix and stronger rental income supported earnings. Contributions from rent-to-own units also helped improve results.
Maynilad, an associate company, recorded its highest earnings, reflecting stronger operating performance. Its contribution to DMCI Holdings, however, declined to P2.2 billion from P2.8 billion a year earlier following the reduction in the group's effective ownership interest after the water distributor's initial public offering in November 2025.
DMCI Mining posted a record contribution of P2 billion, surging 180% from P726 million in the same period last year.
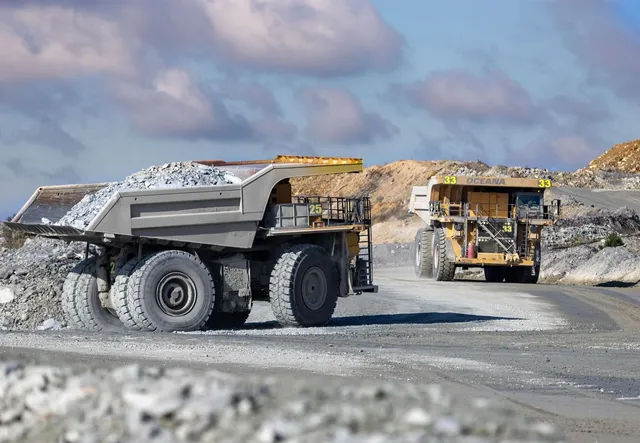
The increase was driven by higher production and shipment volumes following the start of operations at Berong Nickel Corp.'s Long Point mine, bringing the number of active mines to three from two. Higher nickel prices also supported earnings.
DMCI Power contributed an all-time high of P1.1 billion, up 14% from P985 million, on record energy sales, capacity expansions in Masbate and Antique, and stronger wind generation.
Meanwhile, construction subsidiary D.M. Consunji Inc. reported a 76% increase in earnings contribution to P329 million from P187 million, supported by higher profit recognition from joint ventures.
Its construction order book stood at P41.5 billion as of September 2026.
The group's cement business, Concreat, narrowed its attributable net loss by 75% to P402 million from P1.6 billion, reflecting higher sales, improved operating efficiencies and cost management initiatives.
At the standalone level, the cement business generated P1.3 billion in core earnings before interest, taxes, depreciation and amortization, reversing the negative P31 million recorded in the same period last year despite elevated fuel costs.
DMCI Holdings, which has construction and engineering as its core competency, has expanded into real estate, mining, power generation, water distribution and cement. Its businesses operate primarily in the Philippines, with most of its operations located outside Metro Manila.