November 05, 2025

The Philippines has long been known as one of the world’s most mineralized countries, but continues to grapple with unlocking its full mining potential. For decades, red tape, policy uncertainty, and public distrust have kept investors away, even as the country sat atop the proverbial pot of gold.  

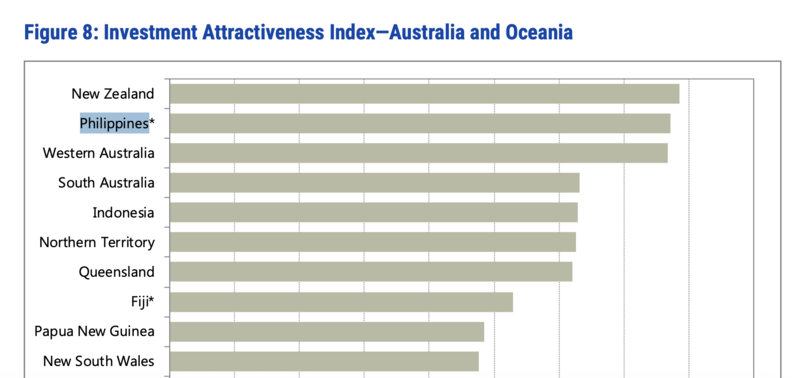
However, this year’s leap in the 2024 Fraser Institute’s Investment Attractiveness Index, from 72nd to 16th place among 82 countries, tells a new story: the Philippines is finally reclaiming its place in the global mining map. 

This turnaround did not happen by chance. It is the result of deliberate policy reforms, sustained regulatory improvement, and a changing mindset within both government and industry.  

The Department of Environment and Natural Resources (DENR) and the Mines and Geosciences Bureau (MGB) have, over the past few years, pursued a vision that balances growth with governance, an approach long overdue in a sector often viewed with suspicion. 

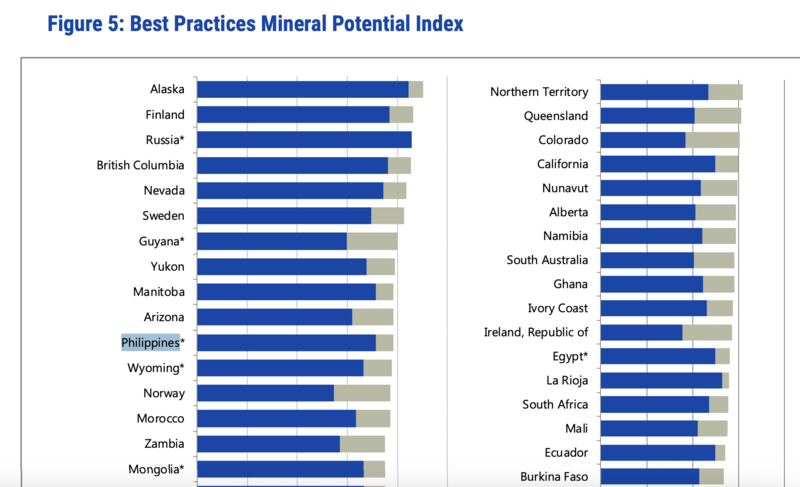
According to the Fraser Institute’s 2024 Annual Survey of Mining Companies, the Philippines’ score nearly doubled: from 36.89 in 2023 to 77.11 in 2024. This surge reflects two critical shifts: a stronger geological attractiveness ranking, now 9th globally, and a dramatic improvement in policy perception, from 79th to 25th. Simply put, the country’s potential is finally matched by a more predictable and transparent policy environment. 

Graph courtesy of the Fraser Institute’s Annual Survey of Mining Companies 2024. 


This progress may be traced to the reforms initiated by former DENR Secretary Maria Antonia Yulo Loyzaga, including streamlined permitting and digital transparency measures, and which are being continued by the current Secretary, Raphael Lotilla. While the aforementioned reforms are largely procedural, they nevertheless translate into predictability and clarity which investors value. 

The numbers tell their own story. In 2024 alone, the mining sector generated ₱253 billion in production value, contributed ₱33 billion in taxes and royalties, and provided nearly 292,000 direct jobs.  

Beyond economics, companies invested billions more in environmental protection, community development, and rehabilitation efforts, proof that responsible mining, once dismissed as an oxymoron, can indeed take root. 

Other signs point to a resurgence in the mining industry.  Aside from the sharp improvement in investment-attractiveness rankings, regulatory, fiscal, and policy reforms have likewise contributed to investor confidence.   

The recent passage of the Enhanced Fiscal Regime for Large-Scale Metallic Mining Act (Republic Act 12253) introduces tiered royalty rates, windfall profit taxes, project-based ring-fencing, and other provisions that aim for fairness, environmental protection, and better revenue sharing.  

Another factor is the rise in production values and asset valuation. Metallic mineral output value has increased mainly due to the “re-entry of projects” [following the lifting of the ban on new mineral agreements in 2021 via Executive Order 130, which allows for new mining projects to proceed]  and strong commodity prices.  The total value of mineral assets rose by 4.6% in 2024 (from ₱460.16 billion in 2023 to ₱481.45 billion) based on Philippine Statistics Authority data.  

The increased global demand, especially for nickel, copper and other “critical minerals,” both from foreign investors and governments (e.g. U.S., China, EU) looking to secure supply chains for technologies like EV batteries, is also a major factor in the renewed attractiveness of the Philippine mining industry.  Since much of the Philippines’ mineral wealth lies untapped, there is a wealth of opportunity for the next wave of responsible mining investment. 

But not everything is rosy. Despite these positive outlook, many challenges remain.  Regulatory enforcement, infrastructure gaps, and inter-agency coordination still need work. Reforms must therefore be sustained to turn optimism into long-term confidence.  

Graph courtesy of the Fraser Institute’s Annual Survey of Mining Companies 2024. 


The Philippines has the potential to become a leading supplier of critical minerals which are essential for the world’s shift to clean energy, but the government and private sector must continue working together. 

The message from the Fraser Index is clear: investors are noticing. The Philippines is no longer seen as a high-risk frontier but as a credible, emerging hub for mineral development in the Asia-Pacific.   

This is a far cry from 2017-2021 when the Philippines ranked much lower in the Policy Perception Index (PPI), often among the bottom 10 jurisdictions. For example, in the 2021 survey, the Philippines was listed among the worst jurisdictions in the PPI. 

Beyond rankings and reports lies a deeper question: what kind of mining future do we want? A future where resources uplift communities and where the wealth beneath our soil powers not just global supply chains but, more importantly, local progress. If the government can sustain reform and accountability, this renaissance will not just be statistical: it will be structural and sustainable. 

The Philippines has taken a major step forward in mining: the real test is to remain sure-footed in sustaining that momentum. 

September 08, 2025

Over the past decade and a half, the Philippine mining industry has experienced a dynamic and often turbulent journey shaped by evolving government policies, environmental activism, shifts in global commodity markets, and new technological and economic priorities.  

From 2010 to 2025, the sector has witnessed sweeping regulatory reforms, the rise and fall of major mining projects, highly publicized environmental controversies, and a renewed focus on mining’s role in the green energy transition.  

Your Philippine Resources Journal has witnessed and chronicled these events over the last 15 years, and as we celebrate our anniversary in this issue, this narrative hopes to unpack the key events, policies, and trends that have defined the PH mining landscape during this pivotal period. 

Early 2010s: Industry Ambitions and Rising Tension 

The start of the 2010s saw heightened optimism within the Philippine mining sector. Policymakers promoted mining as a pillar of national industrialization, encouraging value chain development and community-based mining initiatives. The spotlight fell on projects like Xstrata’s Tampakan copper-gold development, which promised to catapult the country into the ranks of leading mineral exporters.  

However, these ambitions quickly ran into strong headwinds. Environmental groups and local communities intensified their campaigns against large-scale mining, culminating in South Cotabato’s enforcement of a provincial open-pit mining ban in 2011, which effectively stalled the high-profile Tampakan project (now under Sagittarius Mines Inc. or SMI). 

National debates over mining’s true social and environmental costs gained traction, with the Senate holding hearings and grassroots campaigns like “No to Mining in Palawan” galvanizing public opinion. 

2012–2015: Regulatory Shift and Industry Slowdown 

In 2012, President Benigno Aquino III issued Executive Order 79 (EO 79), a landmark policy that imposed a moratorium on new mining agreements while calling for stricter environmental regulations and the rationalization of the sector.  

EO 79 signaled a major policy pivot, prioritizing responsible mining practices and environmental safeguards over unfettered industry expansion. The moratorium brought new investments to a halt, and by 2013, the industry’s contribution to GDP had declined, with mining companies facing mounting criticism for pollution, deforestation, and community displacement. 

Despite these headwinds, the sector maintained a degree of resilience. By 2014, metallic mineral production reached ₱138.6 billion, with nickel emerging as the country’s leading export mineral. The mining industry paid ₱21.4 billion in taxes that year and began expanding environmental and social development programs in response to growing scrutiny.  

In 2015, investments rebounded to nearly US$1 billion, and operations at Didipio (under OceanaGold), Toledo (Carmen Copper), and Coral Bay (Rio Tuba) highlighted the sector’s ongoing economic relevance.  

The Philippines also became a candidate member of the Extractive Industries Transparency Initiative (EITI), reflecting a new emphasis on accountability and global best practices. 

2016–2017: The Gina Lopez Era and Heightened Environmental Scrutiny 

A dramatic turning point arrived with the appointment of Gina Lopez as Secretary of the Department of Environment and Natural Resources (DENR) under the Duterte administration in 2016.  

Lopez launched an unprecedented nationwide audit of mining operations, prioritizing ecological integrity and community welfare above industry profitability. Dozens of mines were suspended or ordered closed for failing environmental standards, and a national ban on open-pit mining was imposed.  

The reforms, while applauded by environmentalists and many local communities, sowed uncertainty throughout the industry and triggered a wave of legal and political challenges. By 2017, Lopez’s tenure had resulted in the suspension of five major operations and the closure of 23 others.  

While the value of metallic production remained stable due to global price increases, the industry grappled with regulatory unpredictability and the prospect of further interventions. The DENR also mandated full EITI participation, reinforcing the administration’s commitment to transparency. 

However, Lopez lasted only one year in the post -- and died in 2019 from brain cancer. She was succeeded at the DENR by former military general Roy Cimatu, who continued the Duterte government’s holding pattern on mining. 

2018–2020: Recovery, ESG Emphasis, and Pandemic Disruption 

With Lopez’s departure, the regulatory climate gradually stabilized. Year 2018 saw a rebound in mining production, as the sector deepened its commitments to environmental, social, and governance (ESG) standards in response to both domestic activism and international investor expectations. However, opposition to large-scale mining remained potent, with ongoing protests and calls for stricter oversight. 

By 2019, the moratorium from EO 79 was still in effect, and exploration budgets stayed low. Major projects like Tampakan and Silangan (under Philex) continued to languish in regulatory limbo. The arrival of the COVID-19 pandemic in 2020 dealt another blow, disrupting operations and supply chains. 

Nevertheless, mining still contributed ₱102.3 billion to the national GDP, with nickel maintaining its status as the top export mineral. Notably, Social Development and Management Program (SDMP) funds were redirected to support pandemic relief efforts in mining communities. 

2021–2023: Policy Reversal and New Growth Drivers 

A watershed moment came in 2021, when Executive Order 130 (EO 130) lifted the nine-year moratorium on new mineral agreements, signaling a more investment-friendly posture while retaining environmental safeguards.  

This policy reversal was driven in part by the growing global demand for so-called “green metals” such as nickel and copper, essential for electric vehicles (EVs) and renewable energy technologies. Gold and nickel production surged, and the industry began to recover from years of stagnation. 

In 2022, the government lifted the open-pit mining ban, further encouraging investment. The DENR promoted exploration for critical minerals, and exports soared to US$7.53 billion.  

By 2023, the value of metallic production reached ₱249.7 billion, with 59 operating metallic mines and a strong focus on ESG. The DENR committed ₱387.95 billion to environmental programs, reflecting the sector’s newfound emphasis on sustainability and social responsibility. 

2024–2025: Mining’s Strategic Role in Green Transition 

As President Ferdinand Marcos Jr. took office, mining was explicitly prioritized as a key component of economic recovery and the national energy transition. Policymakers emphasized downstream mineral processing, seeking to capture greater value domestically rather than exporting raw ore. 

The Mines and Geosciences Bureau (MGB) under the DENR projected a strong outlook for the sector, buoyed by international demand for minerals critical to decarbonization. By 2025, mining was recognized as essential to the Philippines’ green technology ambitions. Nickel demand soared in response to the global EV boom, and draft fiscal reforms proposed tiered royalty schemes to balance government revenue with investor appeal.  

The long-stalled Tampakan copper project was once again under consideration for launch in 2026, symbolizing the sector’s renewed confidence and strategic importance in a rapidly changing world. 

Key Trends and Lessons Learned 

Throughout this period, several overarching trends defined the local mining sector. Policy volatility—marked by alternating waves of restriction and liberalization—had profound impacts on investor sentiment and project viability.  

Environmental scrutiny intensified, with audits, suspensions, and ESG compliance becoming central to mining operations, especially from 2016 onward. The industry’s role in the global green transition brought renewed focus on nickel and copper, transforming them into strategic assets. 

Finally, post-2021 reforms and global market dynamics triggered a revival in investment and exploration, as the Philippines positioned itself to supply critical minerals for a decarbonizing world. 

The trajectory of the PH mining industry over the last 15 years illustrates a complex interplay between resource development, environmental stewardship, social accountability, and economic opportunity.  

As the sector looks ahead, its continued evolution will depend on the delicate balancing of these priorities in the face of both domestic challenges and global shifts – and your Philippine Resources Journal will be here, ready to chronicle these changes. 

September 08, 2025

In the intensifying global race for critical minerals—crucial components in electric vehicles (EVs), renewable energy (RE) technologies, advanced electronics, and other strategic industries—the Philippines stands at a pivotal juncture in this global energy transition. With abundant reserves of nickel, cobalt, copper, and rare earth elements, the country holds in its soil the keys to the 21st-century economy. Yet, without a strategic critical minerals policy, it risks squandering this opportunity, remaining a mere supplier of raw materials rather than ascending the value chain.

A mineral is considered ‘critical’ if it is vital to a country’s strategically important economic sectors. Many governments have clear lists and strategies to safeguard these resources. An alternative to the term ‘critical minerals’ is ‘transitional minerals’ which may be strategic minerals, but not critical in terms of security and the economy. Unfortunately, the Philippines has to define which minerals are considered critical or transitional, let alone a policy that would protect its own resources and ensure a stable and sustainable supply of those minerals.

Nations worldwide are aggressively securing their critical mineral supply chains. A 2025 White & Case survey shows that geopolitics and economic interests—more than climate concerns—is the driving force shaping mining and metals. For instance, China’s state-backed financial institutions have poured over $57 billion in the past two decades into resource-rich countries to tighten Beijing’s grip on critical minerals. Key examples include copper and cobalt from the Democratic Republic of Congo and Peru, nickel from Indonesia, and lithium from Argentina. It now controls roughly 61% of rare earth production and more than 90% of processing capacity, according to the International Energy Agency—power that Beijing has wielded to squeeze its rivals, imposing export controls on a range of critical rare earth minerals, rattling its rival the United States.

Washington has scrambled to respond, imposing tariffs on Chinese EVs and batteries, solar panels, semiconductors, and other products. It has also diversified its supply chains by forging deals far and wide—from securing a mineral deal in war-battered Ukraine to even exploring the purchase of Greenland, to brokering a peace deal between Rwanda and the DRC that could unlock lucrative mineral access to some of the world’s richest deposits of rare earths.

To diversify away from reliance on China and Russia, Canada and Germany signed an accord to deepen cooperation in securing critical mineral supply chains, increase collaboration on research and development, and co-fund new critical mineral projects that support a range of industries—from electric vehicle manufacturing to defense and aerospace.

Other nations are also acting decisively. The European Union’s Critical Raw Materials Act aims to shore up supply chains. In 2024, the EU signed a major agreement with Australia—home to some of the planet’s recoverable critical mineral deposits—to build sustainable and ethical critical mineral supply chains. Australia’s Critical Minerals Production Tax Incentive sweetens the deal for investors with generous tax incentives for domestic processing.

Meanwhile, Canada has committed $3.8 billion to its Critical Minerals Strategy, emphasizing sustainability and Indigenous partnerships. The United Kingdom’s own strategy intends to position itself at the forefront of the green industrial revolution, while Brazil’s National Strategic Pro-Minerals Policy has helped it become one of the top lithium exporters. Closer to home, Malaysia even rolled out its National Advanced Materials Technology Roadmap 2021-2030 emphasizing the need to expand the downstream rare earth industry with the goal of creating a new source of wealth.

The Philippines, with its vast mineral wealth, is well-positioned to become a key player in this global landscape. Recent talks about joining the U.S.-Japan critical minerals agreement shows a clear willingness to engage more strategically. A free trade agreement with Canada focusing on critical minerals is in the works, and just this May, the Philippines signed a strategic pact with South Korea on critical minerals and EV development. And then, the EU, in partnership with the Department of Environment and Natural Resources (DENR), has announced the conduct of a scoping study to identify potential sources of critical raw materials in the Philippines. The study aims to establish a “normative framework” that integrates the best practices of both the Philippines and the EU in promoting sustainable mining and attracting European investment.

However, to truly capitalize on its resources, the Philippines must develop a comprehensive critical minerals policy that addresses supply reliability and resiliency, sustainable and responsible practices, favorable investment climate, and stable regulatory environment.

Indonesia offers a lesson the Philippines cannot afford to ignore. Jakarta’s massive nickel production caused global nickel prices to plummet. For the Philippines, that should be a cautionary tale—highlighting the need to employ price stability mechanisms when striking future trade and investment deals.

If the Philippines wants to entice serious mineral processing investors, it must do more than showcase its mineral wealth—it must build the physical and regulatory infrastructure to move projects from vision to reality. The government has already proven it can cut red tape with the Energy Virtual One-Stop Shop (EVOSS) for energy projects. A similar mechanism could clear the bottlenecks that have long frustrated investors and stalled development.

Beyond economics, critical minerals have become a matter of geopolitics. The U.S., the EU, Japan, and other major economies are racing to secure reliable supply chains that are not dependent on China. This creates a rare window of opportunity for the Philippines to position itself as a trusted and strategic partner in the global transition to clean energy and advanced technologies.

But to truly maximize its potential, the Philippines must move beyond the traditional extractive model. Exporting raw ore captures only a fraction of the value; the real gains lie in downstream industries such as refining, processing, and even component manufacturing for EVs, RE technologies, and electronics. A critical minerals policy that fosters domestic value addition will create jobs, strengthen industries, and insulate the economy from global price shocks.

While the DENR’s issuance of a DAO earlier this year outlining the guidelines for integrating the UN SDGs into the implementation of mining companies’ Social Development and Management Programs is commendable, a critical minerals policy should likewise prioritize sustainable mining practices. Such a policy must craft its own framework that adheres to—and ideally surpasses—international standards on sustainable development in mining, with the twin goals of protecting communities and safeguarding ecosystems.

The effectiveness of any policy will, in large part, depend on the level of trust it is able to build among stakeholders. Investors value regulatory clarity, while communities seek accountability and tangible benefits. Incorporating appropriate safeguards and participatory mechanisms would support the sustainability of the Philippines’ critical minerals policy.

At this pivotal moment, the Philippines cannot afford to remain without a clear roadmap. For the Philippines to claim its rightful place in the global critical minerals supply chain, the time to act—decisively and strategically—is now.


Reeno E. Febrero is senior legal officer at Global Ferronickel Holdings, Inc. He is currently pursuing his Master of Laws at the University of the Philippines, with a thesis focused on sustainable mining.

September 08, 2025

On July 4, 2025, I sat in a crowded forum in Quezon City as the Mines and Geosciences Bureau (MGB) hosted the Department of Environment and Natural Resources’ (DENR) policy direction. The atmosphere was subdued. No questions, no applause lines. Yet the rollout deserves a closer look, not for its promises, but for what it might enable.

Signed in February by former Secretary Ma. Antonia Yulo-Loyzaga, DENR Administrative Order No. 2025-10 requires all Social Development and Management Programs (SDMPs) of mining firms to align with the United Nations Sustainable Development Goals (SDGs).

SDMP is a unique legal requirement under the 1995 Mining Act and its implementing rules that compels mining firms to allocate 1.5% of their operating costs to community programs. For decades, this budget has been channeled into community projects—livelihood support here, a classroom repair there—often valuable, but not necessarily transformative. What DAO 2025-10 does is tether those pesos to something more coherent. From receipts to results.

The 2030 Agenda for Sustainable Development, adopted by 193 UN member states in 2015, sets 17 goals and 169 targets—from ending poverty to protecting biodiversity. Yet the UN warns of slow progress. In the Philippines, the MGB acknowledges gains in key areas but gaps in food security, climate action, and sustainability persist. Paragraph 45 of the Agenda calls on governments to work closely with local authorities.

DAO 2025-10 operationalizes that principle. It channels the SDMP budget toward tangible outcomes like access to clean water (SDG 6), better incomes (SDG 1), inclusive education (SDG 4), biodiversity protection (SDG 15), and decent jobs (SDG 8). The UN Development Programme (UNDP) urged similar reforms in its 2016 SDG-mining atlas while the Intergovernmental Forum on Mining, Minerals, Metals and Sustainable Development (IGF) has long supported this pivot.

On paper, we are catching up. But policies don’t succeed on paper alone. In 2023, nickel miners reported spending ₱4.3 billion on SDMPs. They reforested 9,500 hectares, planted 4.3 million trees, and funded education and health projects. Between 2002 and 2027, nearly ₱28 billion in SDMP spending is projected. But impact isn’t just about inputs. Civil society monitors—like Bantay Kita and local Multistakeholder Monitoring Teams—flag weak community involvement, poor tracking of results, and almost zero public transparency.

To make this reform real, four imperatives must guide implementation.

First, targets must be measurable. “Eradicating poverty” or “protecting forests” can’t just be slogans. The DENR must set clear indicators. How many pesos in income raised? How many hectares rehabilitated? Metrics are meaning.

Second, communities must be co-authors, not mere recipients. The 2030 Agenda says people are at the center of sustainable development. That means participatory planning, stronger local monitoring teams, and respect for Indigenous Peoples’ rights.

Third, SDMPs must be audited independently and disclosed publicly. In 2021, The Asia Foundation—a global nonprofit focused on governance in Asia—underscored how transparency builds public trust. A portion of SDMP budgets should be set aside for third-party audits. Results must be published online, accessible to everyone. SDG 16.6 calls for effective, transparent institutions.

Finally, noncompliance must have consequences. DAO 2025-10 is a regulation, not a wish list. Failure to comply should lead to real sanctions. Without teeth, all we have are good manners.

At the core of this shift is a recurring question: Will the mining governance framework finally serve the common good? In their celebrated book Why Nations Fail, 2024 Nobel laureates Daron Acemoglu and James Robinson argue that long-term prosperity depends on the nature of institutions. Inclusive institutions share power. Extractive ones hoard it. Mining, for all its potential, is often seen under extractive logics—not only in the physical sense, but in how decisions are made, and for whom.

DAO 2025-10 can change that. Not by spending more, but by spending better—linking community projects to real outcomes, and to a global development framework.

But good rules aren’t enough. It takes leadership to embed accountability into the system. And that falls on the shoulders of DENR Secretary Raphael Lotilla, who is known for his technocratic rigor and institutional calm. He doesn’t need to invent new tools. He just needs to make sure the ones we already have are tried, tracked, and trusted.


Noel B. Lazaro is General Counsel of Global Ferronickel Holdings, Inc. He was named among Top 5 In-House Counsel of the Year at the 2024 Asian Legal Business (ALB) Philippine Law Awards and has led his team to multiple regional and national honors.

September 08, 2025

In August, I attended the launch of Unilab Education (UniEd), the Unilab Group’s response to a longstanding national challenge: the mismatch between graduates’ skills and the available jobs.   

At this event, attended by the Secretary of Education, the Director General of the Technical Education and Skills Development Authority (TESDA), the Chair of the Commission on Higher Education (CHED), industry leaders and heads of educational institutions discussed the need to reshape how education is delivered and ensure that Filipino graduates are job-ready. 

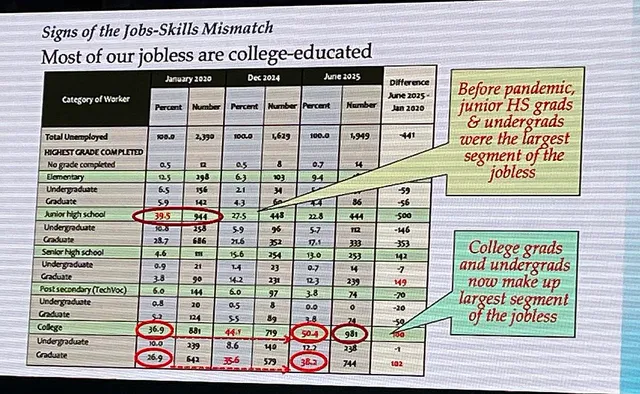
In his keynote address, Dr. Cielito Habito, former Secretary of the National Economic and Development Authority (NEDA, recently renamed the Department of Economy, Planning, and Development or DEPDev under Republic Act No. 12145), delivered some disturbing statistics, including that college graduates now account for the single largest segment of the unemployed at 38.2%. He emphasized the need for integrated education and workforce development planning, closer coordination in curriculum design, and better anticipation of future skills demand. 

Equally, if not more disturbing was the recurring observation that the concerned agencies, namely the Department of Education, TESDA and CHED, have not been properly coordinating.  Simply put, until recently, they were not talking to each other.  Fortunately, these agencies have come to the realization that closer inter-agency collaboration is required to achieve to stronger industry alignment and policies that improve graduate employability. 

UniEd, for its part, is batting for industry certifications, microcredentialing [i.e., earning short, modular certifications for specific, in-demand skills, enabling workers to upskill, reskill, gain formal recognition for competencies, and advance in their careers without completing an entire degree or lengthy course], apprenticeship and on-the-job training, senior high school immersion, and skills-based continuing professional development courses to specifically address the jobs–skills mismatch. 

An Ernst & Young paper entitled “Can ASEAN move forward if women are left behind?” observes that, with 40% of global employers today reporting talent shortage, education systems need to prepare graduates with relevant skills.  

In ASEAN, the skills gap is largely marked by a shortage of technical knowledge. Science, Technology, Engineering and Mathematics (STEM) education is therefore particularly relevant given rapid technological shifts and the rise of industry automation, alongside the emphasis on infrastructure development in many emerging ASEAN economies.  

In the Philippines, the skills gap is very much pronounced with the country having the lowest gender parity in the region.  It records the widest STEM workforce gender gap in AsiaPacific, with women in just 36.3% of STEM roles, compared to nearly 59% in non-STEM fields.  Although around 41% of STEM graduates are women, only 36.6% enter the STEM workforce within a year from graduation.  

The decline continues as careers progress. Employers cite that women are less prepared due to fewer internships or technical opportunities. Many mid-career women opt out due to caregiving demands or biased perceptions. 

Mining is one industry that would benefit from a closer look at how STEM Education may help close the jobs-skills mismatch, especially for women. 

The convergence of mining and STEM offers unique opportunities to counteract gendered mismatches: 

  • Empowerment via technical training: Tailored STEM education programs could equip women miners with essential competencies to open pathways to formal, technical roles. 

  • From informality to formal inclusion: Launching bridging programs that connect women in small-scale mining to technical certification and STEM jobs can reduce informal vulnerabilities and prepare them for emerging green technologies in mining. 

  • Visibility and leadership: Mentorship programs and representation are required to boost women in the workforce. Highlighting female engineers, geologists, and other female leaders can inspire younger women to pursue both STEM and mining careers.  

In the aforementioned Ernst & Young paper, Ambassador Delia Domingo Albert, Chairman of Diwata-Women in Resource Development, Inc., noted that “(T)here are horizontal gaps that consist of development gaps between and among the member countries, as well as gender equality gaps. There are also the vertical gaps between women who are well-educated and have better access to leadership roles and those who have fewer possibilities and are stymied by economic and social circumstances. These gaps hinder the possibilities for leadership roles.”  

STEM Education may help close this vertical gap through, among others, better designed curricula to anticipate both current and future skills demands; targeted technical training; and more vibrant academe-industry exchanges [with teachers immersing themselves by working in firms to improve their own skills and ‘real world’ application of what is being taught]. 

STEM education is also the backbone of a responsible, sustainable, and competitive mining industry in the Philippines.  It ensures that local talent can fill technical roles, reducing reliance on foreign experts, and also fosters innovation in exploration, extraction, safety, and sustainability. 

With these institutional shifts, and reimagined narratives, we can create pathways where women not only participate, but thrive, in the mining and STEM sectors. 
September 08, 2025

In our ever-evolving world, the demand for minerals and energy is growing faster than ever. From the smartphones in our pockets to the electricity powering our homes, these natural resources play a vital role in our everyday lives. But finding them—hidden deep underground or beneath the ocean floor—is no easy task.  

Fortunately, science and technology are giving us powerful new tools to make searching easier, safer, and more accurate. Understanding new mineral and energy exploration techniques is important because the relatively easy-to-find resources—like oil, gold, and copper—are already being used up, and the world needs cleaner and smarter ways to discover what’s left. Old methods of exploration, like drilling everywhere or clearing forests, are expensive, slow, and often harmful to the environment. 

New technologies, like using satellites, artificial intelligence (AI), and sensors that “listen” to the ground, help scientists find resources faster, cheaper, and with less damage to nature. By learning how these new techniques work, we can support energy sources that are cleaner, protect the planet, and ensure we still have the minerals needed for things like electric cars, solar panels, and everyday gadgets in the future.  

Here is an overview of the latest technological trends in mineral and energy exploration—combining cutting‑edge research, practical implementations, and industry shifts. We'll explore some of the latest techniques scientists and engineers are using to discover new sources of minerals and energy. Don’t worry—no geology degree is required! This article will break it down in simple, easy-to-understand language so we can understand just how incredible and important these discoveries really are. 

AI-Powered Exploration, Smart Computers Find Hidden Treasures 

Recent research introduces workflows using AI to model copper prospectivity and refine targets. Presently, roughly more than 70% of mineral exploration projects leverage AI‑powered data analysis for site selection and resource estimation. Machine learning applied to remote sensing like integrating satellite, airborne, and geological data, has enhanced mapping of lithology, alteration zones, and pathfinder mineral signatures. 

Imagine you’re looking for buried treasure, but instead of digging randomly, you have a super-smart computer that can look at maps, satellite images, rock samples. and even underground sound waves to tell you exactly where to dig. That’s what AI is doing for mining, helping experts find metals like copper, lithium, and gold faster and more accurately. This technology saves millions of dollars and years of guessing because there are less random digging and more smarter decisions. 

Advanced Remote Sensing: Satellites, Drones as “Metal Detectors in the Sky” 

Today, scientists are using advanced hyperspectral satellite cameras that can see more than just colors; they can detect the unique "light fingerprints" that different minerals reflect. This helps spot what’s in the ground just by looking from space. Some high-tech companies are going even further. They’re launching small satellites, placing sensors on the ground, and using AI to collect and analyze data.  

Satellites in space and drones flying overhead are now like "robot eyes" scanning the Earth for clues about what’s underground. Satellites can see patterns in rocks that the human eye can’t. Drones fly low over the ground with special cameras and sensors that “sniff out” changes in rocks or soil. This technology allows explorers to scan vast areas quickly, especially in places that are hard to walk on like dense forests or deserts, useful even in difficult terrain and across larger areas.   

Listening Beneath the Ground with “Earth Stethoscopes” 

Imagine a drone that can take off and hover like a helicopter but then fly forward like an airplane. That’s what a hybrid multirotor unmanned aerial vehicle (UAV) does. It gives you the best of both worlds: the flexibility of hovering and the long-range power of flight. Hybrid multirotor UAVs with optimized sensors extend airborne operations up to six times longer than traditional drones, improving precision data collection while minimizing costs and environmental impact.  

By placing special sensors on the surface, explorers are also listening to tiny natural vibrations in the Earth —like a super-sensitive stethoscope — to create detailed 3D maps of what lies underground, even as deep as 2.5 kilometers without digging. Instead of drilling hundreds of holes to “see” underground, scientists now listen to tiny vibrations called ambient noise tomography. All of this helps explorers find mineral-rich areas more accurately and safely, while cutting down on the need for risky and expensive drilling. 

Tools That are Instant Rock Analyzers: On-the-Spot X-Rays 

When geologists collect rock samples, they used to wait days or weeks to analyze them in labs. Now, geologists can carry handheld devices—about the size of a power drill—that can scan rocks right on the spot. These tools use techniques like X-ray fluorescence (XRF) or laser-based scanning to instantly reveal the chemical makeup of the rock. In just a few seconds to a few minutes, the device tells you exactly what minerals or metals are inside—whether it’s copper, gold, lithium, or something else. It’s like a super-advanced metal detector that gives instant X-ray results. 

Think of these machines as a super-smart barcode scanner, but for rocks. Just like a grocery store scanner instantly tells you the price and details of a product, these scanners reveal what elements are inside the rock. This means faster decisions, less wasted drilling, and more precise resource estimates. 

Sustainable Practices & Resource Recycling: Mining “Junkyards” 

Old mines and heaps of mining waste were once considered useless. Now, with new technology, companies can go back and recover valuable metals left in old mine tailings. Exploration is increasingly seeking value in waste and tailings, repurposing old mines to extract critical metals like tellurium, bismuth, zinc, and manganese. It’s like rummaging through old electronics and finding out that old circuit boards are filled with precious metals or finding gold in an old junkyard - eco-friendly and cheaper than starting a new mine. 

Mining Under the Sea: Carefully Collecting “Seafloor Nuggets” 

At the bottom of the ocean, there are “potato-sized” lumps called polymetallic nodules that contain nickel, cobalt, and other valuable metals. New technology is being developed to allow controlled collection of these nodules without digging or destroying the seafloor. It’s like using robotic vacuum cleaners to gently pick up scattered coins from your carpet, without ripping the carpet up.  

This could be a game-changer for supplying metals for electric cars and renewable energy tech, but it’s being done cautiously to protect ocean ecosystems. Deep-sea mining is now under active development globally, with regulatory frameworks expected to be in place by 2025. Think of it like careful underwater treasure hunting with environmental guards in place. 

Tapping Into Earth’s Natural Heat: Hitting Two Birds with One Stone 

The Earth’s inside is super-hot. By drilling wells, we can tap into this heat to produce clean electricity called geothermal energy. But here’s the bonus - some of these underground hot waters carry dissolved minerals like lithium. New projects are combining the two: get clean energy and extract minerals from the hot water. It’s like getting two gifts from the Earth at the same time - energy and minerals, like boiling pasta and realizing you can also make soup from the water at the same time.  

Geothermal energy is expanding rapidly. Major tech companies and energy firms are investing in subsurface heat projects, but serious skill gaps exist in geoscience expertise, driving demand for trained exploration professionals. Filipino geologists who are renowned for their expertise in geothermal energy, can skillfully harness the Earth’s natural heat to power communities with precision and sustainability. Their deep understanding of volcanic and tectonic systems, combined with decades of hands-on experience, has positioned the Philippines as a global leader in geothermal exploration and development. 

Mines Becoming Smart, Automated Like Self-Driving Cars 

The mining sector is undergoing a digital revolution; automation, and integrated data analytics are being deployed broadly to enhance safety, productivity, and sustainability. Modern mines are starting to use robots, self-driving trucks, and smart sensors that monitor everything. All this information is sent to a control room where a small team watches everything like in a high-tech video game command center. This makes mining safer for workers and cuts down on mistakes and accidents. Real-time predictive maintenance, remote operations control, and cross-team data sharing are boosting operational effectiveness by a 20–30% reduction in exploration timelines and cost improvements. 

Industry is responding with technology-integrated, sustainable, and data-first approaches. From satellite mapping to automated analytics, these capabilities shorten discovery cycles, cut environmental impact, and strengthen resilience. There is less guesswork as technology tells you where to dig; greener, exploration is becoming cleaner and less harmful to forests, rivers, and wildlife; smarter as mining is done in ways that protect the environment; sustainable as old waste becomes valuable again through recycling; faster as years of trial-and-error digging are minimized; and cheaper as there is less wasted money on bad drilling spots. 

The Gold Rush of the Clean Energy Era: The Search for White Hydrogen 

Hydrogen is the lightest and most abundant element in the universe. It is found in water, natural gas, and even in plants and animals. But here’s the catch: hydrogen gas doesn’t float around freely on Earth. It’s usually stuck to other elements, like oxygen in water. We need hydrogen to power cars, factories, and power plants without polluting the air.  Planes and large ships could run on hydrogen in the future. Companies are working on hydrogen-powered engines or using hydrogen to make cleaner fuels for heavy industries. Hydrogen is a clean fuel. When you burn it, it only produces water vapor - no smoke, no CO₂ pollution. 

Exploring natural hydrogen could give us a cheaper and greener source of energy that’s available 24/7, unlike solar or wind which depend on weather. Scientists have discovered that pure hydrogen gas is naturally produced deep underground. This hydrogen can slowly seep up through cracks in the Earth, kind of like natural gas or oil. 

When certain types of rocks that are rich in iron deep in the Earth react with water, they produce hydrogen gas. This process happens in places like ancient volcanic areas, underneath old ocean floors, and tectonic plate boundaries. Like a treasure hunt under the earth, scientists use several clues to look for it. 

In some places, hydrogen gas seeps up naturally through the soil, kind of like tiny invisible “fountains.” Scientists use portable gas sniffers or take soil gas samples to detect these hydrogen leaks. Finding a seep can be a clue that a larger hydrogen pocket is hiding underground. Hydrogen often forms where certain types of iron-rich rocks called ophiolites react with underground water. Scientists study maps, satellite images, and rock samples to locate areas with these special rocks. 

Scientists use tools that send sound waves, electric currents, or magnetic signals into the ground. By seeing how these signals bounce back, they can “see” underground structures and guess where hydrogen might be trapped. If the clues are strong, companies drill small test wells to check if there’s enough hydrogen to be worth collecting. This is like how we explore oil or natural gas, but the wells for hydrogen are usually smaller and simpler. 

The Philippines is now at the early but exciting stage of exploring natural underground hydrogen resources, after a significant discovery in Zambales. In this area, scientists found a natural seep where hydrogen gas is leaking from beneath the ground at a remarkable rate—about 808 tons per year, which is considered one of the largest natural hydrogen flows ever recorded worldwide. This seep is found in an area rich with ophiolite rocks, which the country has plenty of because of its geological features. This discovery has put the Philippines on the global map as a potential key player in the emerging hydrogen energy sector. 

Recognizing this opportunity, the Department of Energy (DOE) has opened specific areas for hydrogen exploration in Zambales and Pangasinan, where similar rock formations exist. Several companies have submitted bids to explore these zones, and the DOE has been actively conducting preliminary surveys to assess the environment and geology. These early-stage activities include soil gas sampling, mapping seep sites, and preparing technical guidelines for future exploratory drilling. 

The DOE is also initiating training programs to equip Filipino scientists and engineers with the skills needed for hydrogen exploration, signaling a serious commitment to develop local expertise in this new field. 

While no large-scale hydrogen production is happening yet, the Philippines is moving swiftly to build a foundation for it. The next steps involve granting exploration permits, performing test drilling, and confirming whether larger underground reservoirs of hydrogen exist beneath the surface. If successful, this could lead to pilot projects that produce clean hydrogen for local energy use, particularly in off-grid rural areas.  

The exploration efforts in Zambales and Pangasinan are also seen as “test cases” that could open other ophiolite-rich regions in the Philippines, potentially making the country a pioneer in natural hydrogen energy development in Southeast Asia. Thanks to years of digging into ancient ophiolites, Filipino scientists may have just found the rocks that burp out clean hydrogen turning old ocean crust into tomorrow’s energy goldmine. 

Conclusion 

As the world races towards cleaner and more sustainable energy solutions, understanding and adopting new mineral and energy exploration techniques has never been more crucial. Innovations like AI-driven mineral mapping, drones that “see” underground, instant rock analyzers, and natural hydrogen exploration are revolutionizing how we discover and harness Earth’s resources.  

The Philippines has rugged terrain and extensive forest cover. AI-driven satellite imaging and drone-based surveys are increasingly useful for identifying mineralized zones without heavy ground disturbance. This helps reduce the environmental footprint of early-stage exploration.  

By adopting smarter targeting, Philippine mining firms can reduce the high risk and costs of exploration, making projects more attractive to investors, reducing the need for large-scale ground clearing during exploration, and helping address community and environmental opposition. This is important in a country where mining often sparks social resistance, as it could accelerate the development of critical mineral supply chains while improving the sector’s social acceptability. Who knew that listening to rocks and chasing steam could turn geologists into the hottest hunters of the 21st century? 

References 

Barker, Miranda, Innovation can disrupt the mining industry. These sustainable start-ups are leading the way, World Economic Forum, 29 Nov 2024, https://www.weforum.org/stories/2024/11/13-innovations-making-the-mining-and-metals-industry-more-sustainable/ 

Bishop, Sophie, 7 Technological Innovations Transforming the Mining Industry, USC Consulting Group, 12 February 2024, https://usccg.com/blog/7-technological-innovations-transforming-the-mining-industry/ 

Leonida, Carly, Welcome to the age of smart mineral exploration, The Intelligent Miner, 06 June 2024, https://theintelligentminer.com/2024/06/06/welcome-to-the-age-of-smart-mineral-exploration/ 

Peachey, Caroline, How is technology shaping minerals exploration? Mining Technology, 17 April 2025, https://www.mining-technology.com/features/how-is-technology-shaping-minerals-exploration/ 

Fernando “Ronnie” S. Penarroyo specializes in Energy and Resources Law, Project Finance and Business Development. He is also currently the Chair of the Professional Regulatory Board of Geology, the government agency mandated under law to regulate and develop the geology profession. For any matters or inquiries in relation to the Philippine resources industry and suggested topics for commentaries, he may be contacted at fspenarroyo@penpalaw.com. Atty. Penarroyo’s commentaries are also archived at his professional blogsite at www.penarroyo.com  

July 29, 2025

By Ronald S. Recidoro, Executive Director, Chamber of Mines of the Philippines

After more than a decade of uncertainty and policy flip-flops, the reconciled version of the Mining Fiscal Regime Bill, once signed, will mark a turning point in Philippine mineral policy. It is not just the culmination of years of legislative advocacy; it is the resolution to a long-standing national debate on how we can get the most out of our mineral wealth.

The final measure, based largely on Senate Bill No. 2826 (with the ore export ban wisely removed), charts a pragmatic path forward. It aligns the government’s revenue ambitions with investor requirements and finally offers the mining sector the regulatory clarity it has long prayed for.

A Law a Decade in the Making

When President Aquino assumed office in 2010, the industry had high hopes that mining would get its fair share of the government’s attention. Riding on the 2004 Supreme Court decision upholding the constitutionality of RA 7942 in La Bugal-B’laan vs. Ramos, and the Arroyo administration’s full-throated call for investments in the mining industry, the sector was on an upswing, posting 9% growth in 2010–2011. This, plus the size of the country’s estimated mineral reserves, then valued at US$1.38 trillion (approx. ₱77.0 trillion), seemed to position the country for a mining revival not seen since the 1980s. But rather than continue the momentum, the Aquino administration slammed on the brakes, influenced by counter-narratives that emphasized mining’s environmental costs while overlooking its economic potential.

In 2012, President Aquino issued Executive Order No. 79, imposing a moratorium on mining applications pending the passage of a new fiscal regime. While EO 79 recognized existing tenement rights, it also expanded no-go zones, created additional review layers, and generated policy confusion.

That same year, the Department of Finance proposed a new fiscal regime under House Bill No. 5367, which sought to impose either a 10% royalty on gross output or 55% of adjusted net mining revenues, whichever yielded higher revenues for the government. Though the bill underscored the administration’s goal to extract a greater share in mineral resource revenues, its punitive structure failed to strike a balance between state interest and investor viability. No consensus was reached, and the bill languished. As policy drifted, mining investment collapsed by 43%, from US$1.37 billion projected in 2012 to just US$800 million by year-end. The de facto moratorium persisted, and by then, it was clear: without a rational and competitive fiscal framework, there could be no future for large-scale mining in the Philippines.

The Duterte administration offered little reprieve. It began with a crackdown under then-DENR Secretary Gina Lopez. Suspensions, closures, and a biased audit process reaffirmed investors’ fears that the government still pushed the anti-mining narrative. However, a glimmer of reform emerged in Congress through House Bill No. 288, authored by Rep. Estrellita Suansing. The bill introduced, for the first time, a progressive margin-based royalty and a windfall profits tax. Though the bill failed to pass during that 18th Congress, it laid the groundwork for what would eventually become House Bill No. 8936 and Senate Bill No. 2826.

Armed with nothing but patience, the industry waited. Instead of fighting City Hall, mining companies followed instructions by improving their technical capacities and raising their standards, implementing ISO 14001, EITI, and TSM standards, all while lobbying for change. But as the Industry tread water, the window of opportunity narrowed further, and we fell behind our peer countries in attracting quality investment.

While President Duterte did lift his mining moratorium in the waning days of his term, it wasn’t until the Marcos administration that we saw real momentum. With a practical view of mining as a key driver of economic resilience, the administration reopened the door. Through sustained efforts by the Department of Finance, DENR, MGB, and industry stakeholders, we now have a reconciled fiscal regime bill that achieves what EO 79 never did: a coherent, progressive, and competitive law that balances risk and reward for all stakeholders.

The bill introduces a modern fiscal structure intended to make government revenue from mining operations more responsive to profitability, while also addressing long-standing demands for greater transparency, equity, and local benefit sharing. At its core, the bill adds to the current mineral excise tax system a new, progressive royalty regime. It also introduces a windfall profits tax (WPT), applies project-level ring-fencing, and enhances the revenue-sharing mechanism for local governments. Notably, the bicameral committee removed the proposed ore export ban, acknowledging real gaps in local processing capacity, power infrastructure, and investor readiness, thereby allowing the country to continue exporting ores while addressing the real challenges to attracting downstream investments.

Key Features of the Consolidated Bill

The consolidated mining fiscal regime bill introduces a more progressive and responsive framework for taxing the mining industry, one that aligns the Philippines with global best practices in extractives taxation. Projects located within mineral reservations will continue to pay a fixed royalty of 5% on gross output, while those operating outside reservations will be subject to a flexible, margin-based royalty structure ranging from 1% to 5%, depending on operating profit margins. Importantly, in cases where a project records zero or even negative margins, a minimum royalty of 0.1% on gross output still applies. This minimum royalty further affirms the State as owner of the minerals, ensuring that it receives a baseline share from all operations, even in downturns. This mechanism avoids the rigidity of flat-rate systems like Zambia’s and introduces fiscal resilience in both high and low commodity price cycles.

At the upper end of the scale, the bill introduces a windfall profits tax (WPT) that applies to net income once a project’s profit margin exceeds 30%. The WPT starts at 1% and increases progressively to a maximum of 10% for margins above 75%. This structure is broadly consistent with the approaches taken by countries like Chile and Peru, which tax extraordinary profits during commodity booms while maintaining competitiveness during normal years.

To ensure integrity in the tax system, the bill incorporates a ring-fencing provision that treats each mining project or agreement as a separate taxable unit. This prohibits cross-project cost offsets and promotes clearer, project-level revenue attribution, a practice aligned with OECD recommendations on project-based reporting. The bill also tightens restrictions on related-party debt through a thin capitalization rule that caps interest deductions at a debt-to-equity ratio of 2:1. This cap is stricter than Indonesia’s, consistent with Brazil’s, and more conservative than Australia’s, reflecting a deliberate effort to prevent base erosion and profit shifting while remaining within globally accepted norms.

The bill also seeks to equitably distribute mining revenues across levels of government. Forty percent of total government revenues from mining operations will be allocated to host local government units (LGUs), with a mandated release period of no more than six months after receipt of payment. Additionally, 10% of collected royalties will go to the Mines and Geosciences Bureau (MGB) and the Metals Industry Research and Development Center (MIRDC), reinforcing the state’s ability to regulate, monitor, and develop the industry effectively.

Transparency is institutionalized as a core principle of the regime. The Department of Finance is mandated to establish a fiscal transparency mechanism specific to the extractive sector, with an obligation for annual disclosure of company-level financial, tax, and environmental information. This mirrors the evolving international emphasis on open data and public oversight in natural resource governance, as championed by initiatives such as the Extractive Industries Transparency Initiative (EITI).

Taken together, these features position the Philippines to both increase government revenue from mining and offer a stable, predictable framework for investors, while reinforcing transparency, fairness, and alignment with global benchmarks. From a national fiscal standpoint, the Department of Finance estimates that the new regime will yield ₱6.26 billion in incremental revenues annually between 2025 and 2028, a figure higher than the House version and reflective of a more nuanced approach to taxing operating margins. At the local level, the law also promises to generate substantial developmental gains. Forty percent of government revenues from mining will be remitted directly to host local government units (LGUs), with mandated release within six months of collection. With reliable and regular releases of LGU shares ensured, this provision should enable mineral-rich provinces like Palawan, CARAGA, and South Cotabato to make sustainable development plans using their shares. Moreover, 10% of all royalties collected will be earmarked for the MGB and MIRDC to strengthen their regulatory, monitoring, and developmental functions. With only 50 or so large-scale metallic mines currently operating in the Philippines but occupying less than 0.02% of the country’s land area, this law has the potential to scale up both revenue and employment from mining without expanding the industry’s physical footprint.

Some Policy Concerns

Despite these gains, a cautious reading of the bill raises several serious concerns. First, the revenue forecasts assume stable metal prices, an expanding project pipeline, and improved investor confidence. Given the current global geo-political dynamics and our own government’s penchant for flip-flopping on mining policies every change of administration, these assumptions may not always hold. High-profile projects such as Tampakan, Kingking, and the Far SouthEast Project remain stalled due to unresolved permitting issues, regulatory flip-flopping, and legacy LGU and IP issues. Without a concerted effort to streamline permitting, lift outdated restrictions, and enforce clear policy alignment across agencies and local governments, the envisioned revenue gains may never materialize.

Second, the structure of the minimum royalty imposes a troubling distortion. When a mining project with high gross output but temporarily negative margins falls below zero profit, it must still pay 0.1% of gross output as a minimum royalty. This can result in higher tax obligations than if it had posted a narrow profit. For example, a company with ₱10 billion in gross output and a -0.5% margin would owe ₱10 million in royalty. In contrast, the same company with a +0.5% margin might owe significantly less under the margin-based sliding scale. This absurd but plausible scenario effectively penalizes distressed or reinvesting mines, contradicting the policy’s stated intent to support marginal operations and manage cyclical risk. A deferred royalty mechanism, or one based on net smelter return rather than gross output, may have offered a more rational approach.

Third, ring-fencing and thin capitalization rules, while sound in theory, may impose unintended costs. By disallowing cross-project costs and restricting intercompany financing flexibility, these provisions could deter companies from developing higher-risk or early-stage projects. They may also raise financing costs, especially for companies relying on intra-group lending to absorb high upfront capital expenditures common in exploration and development.

Fourth, while LGU revenue sharing is a welcome reform, the actual absorptive capacity of many host LGUs to plan and make the best use of their shares in national wealth taxes remains weak. These expedited releases must translate into tangible community investments, especially in health, education, and resilience. However, without meaningful capacity-building, fiscal transparency measures, or development planning support, there is a risk that windfall revenues could be poorly managed or diverted to non-priority expenditures, undermining the very goal of inclusive development.

The implementation of the windfall profits tax is also likely to be complex. Accurately assessing profit margins in mining is notoriously difficult due to fluctuating costs, commodity price volatility, and varying interpretations of deductible expenses. Without significant upgrades to the BIR’s technical capacity and the issuance of clear, administratively feasible rules, the WPT could become a source of protracted audit disputes, uncertainty, and litigation.

Finally, while the bill correctly deleted the export ban, it fails to put forward a coherent strategy for downstream processing. The problems and challenges to competitiveness that the industry flagged during the Duterte administration are still unaddressed. There is still no national roadmap for value-adding through domestic refining or smelting. Without one, the Philippines risks being locked as a raw material exporter in an increasingly competitive regional market where countries like Indonesia and Australia are aligning their mineral policies with the global transition to clean energy, electric vehicles, and battery manufacturing. A practical critical minerals roadmap, similar to Indonesia’s EV-battery strategy, is urgently needed to jumpstart the vision of adding more value to our raw minerals.

It is also important that we not oversell the idea of mining being an economic game-changer for the Philippines. While the reform does enhance our fiscal and policy stability, it cannot compensate for the fact that the Philippines lacks large reserves of rare earths or critical minerals beyond lateritic nickel. Indonesia, on the other hand, not only boasts the world’s largest nickel reserves but also holds a dominant 61% share of global refined nickel production. By comparison, the Philippines has about 4.8 million tonnes of contained nickel (≈3.7% of global reserves), ranking sixth globally, and produced 330,000 tonnes of contained nickel ore in 2024, about 9% of global output.

In sum, while the mining fiscal regime bill brings long-overdue stability and clarity to an industry paralyzed by policy ambiguity, its economic potential will only be realized through aggressive implementation, regulatory reform, and a broader national minerals development strategy. The government must now move swiftly to issue clear rules, build institutional capacity, and lift the remaining non-fiscal constraints on mining. Only then can the Philippines harness its mineral wealth not just as a revenue stream, but as a platform for industrial transformation and inclusive growth. This reform is a critical first step, but it does not make us a mining powerhouse. With realistic expectations and focused implementation, however, the Philippines can still become a credible and responsible player in the global minerals supply chain.

Next Steps and Recommendations

Moving forward, the Industry must engage actively with the government in the drafting of the law’s implementing rules, with particular focus on clarifying how margins will be calculated and what deductions will be allowed, how the windfall tax thresholds will be applied and phased in, and how ring-fencing rules will treat co-located projects sharing the same manpower, equipment, and infrastructure.

We will need to coordinate closely with the DOF, MGB, and BIR to ensure that compliance tools are practical and that there is adequate transitional support for projects that may be significantly affected. At the same time, we need to keep pushing the government to address existing challenges and create stronger incentives for downstream processing. This can be achieved through future legislation or administrative policies to enhance the Philippines’ competitiveness in mineral value-adding.

Finally, we should keep a close watch on how this new fiscal regime impacts marginal projects on the ground and be ready to advocate for appropriate forms of transitional relief where justified.

Conclusion

The passage of the reconciled mining fiscal regime bill marks a pivotal moment in the long and difficult effort to craft a fair, forward-looking policy for the mining sector. The framework it offers is progressive yet pragmatic. It is designed to give the government a greater share when profits surge, while offering protection and predictability for investors during leaner periods. Crucially, it acknowledges the high-risk, capital-intensive nature of exploration and development. Without globally competitive returns, responsible players will continue to look elsewhere.

The bicameral version of Senate Bill No. 2826 represents real progress. It removes the contentious ore export ban while putting in place a more balanced and transparent tax structure. But its passage is not the finish line. The real work begins with implementation: ensuring that the IRR is clear and practical, that agencies are adequately resourced, and that transition measures are in place for marginal or legacy projects.

If we are serious about making mining a real contributor to national development, the government and private sector must now work even harder to address long-standing structural issues: streamlining permitting, fixing inter-agency bottlenecks, aligning national and local development goals, and ensuring the highest standards of environmental and social responsibility.

From the issuance of EO 79 in 2012 to the finalization of this bill, the road has been long, often uncertain, and politically fraught. But we have finally arrived at a point of clarity. We now have a fiscal regime that reflects hard-won compromise, sound economics, and, above all, a vision for shared prosperity. This is our opportunity to restore trust between the government and investors, between industry and communities, between economic growth and environmental integrity. It is now up to all of us to follow through with good governance, targeted investment promotion, and a deep commitment to sustainability.


For those who want to better understand what this new fiscal regime means, not just for government or industry, but for communities, investors, and the broader development agenda, we invite you to join us at MINING PHILIPPINES 2025, happening on October 22–23, 2025, at the Grand Hyatt Manila, Bonifacio Global City. This will be the first major industry gathering following the law’s passage, and it promises to be an important venue for dialogue, clarification, and collaboration as we move from policy to implementation.

July 08, 2025

The interplay of geopolitics and natural resources has become increasingly pronounced in modern times, with countries vying for access to critical minerals vital for economic and technological development.

Recent events, such as the hostility between Israel and Iran, with the United States striking Iran’s three nuclear sites, have significant ripple effects on resources globally, especially on energy, supply chains and humanitarian aid.

Even without the current tensions in the Middle East, geopolitical interests have been seen as a major driver of activity for mining and metals.

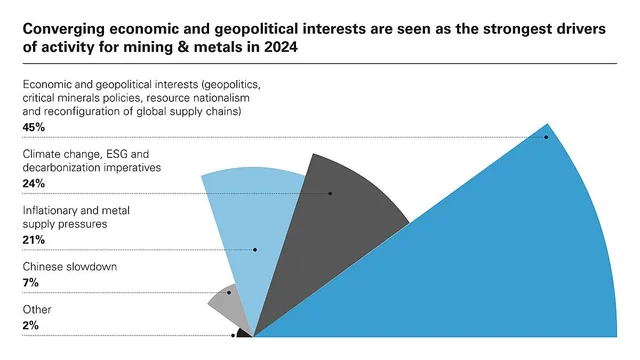
In a 2024 study among developed markets conducted by White & Case, 45% of respondents identified economic and geopolitical interests (geopolitics, critical minerals policies, resource nationalism and reconfiguration of global supply chains) as the top driver, followed by climate change, ESG and decarbonization initiatives (24%); inflationary and metal supply pressures (21%); Chinese economy slowdown (7%); and other factors (2%).

Supply chain disruptions are also seen as the biggest potential impact of geopolitical tensions (58%), followed by slowdown in actual commodity demand and deflationary pressures from slow growth (27%).

While geopolitics may be seen as impacting natural resources, it has long been posited that our requirements for natural resources in fact dictate geopolitical dynamics, which influence nations’ interactions on the global stage.

Some factors which have led to the rise of natural resources in the determination of geopolitics and the growing competition for access and control of resources include “rapid industrialization, rising demand for energy, emergence of new markets and depletion of natural resources at a disconcerting rate.” [“Geopolitics of Natural Resources” (2012) by Nishtha Chugh]

In a paper entitled “Resources: Geopolitics Around IT” [Bhawani Prasad Sharma (2022), four points of significance of natural resources in shaping international relations were identified:

  1. Economic significance: Natural resources, such as oil, minerals, and agricultural products, are essential for economic development. They drive industries, generate revenue through exports, and are critical for maintaining a country's economic stability and growth.
  2. Strategic significance: Control over certain resources can confer strategic advantages. For example, oil-rich countries often wield significant influence in global affairs due to their ability to impact energy markets. Similarly, access to rare minerals essential for high-tech industries can be strategically advantageous.
  3. Political Significance: Natural resources can influence political dynamics within and between countries. Resource abundance can lead to conflicts over control and distribution, while resource scarcity can create vulnerabilities and drive cooperation or competition for access.
  4. Environmental Significance: The exploitation of natural resources can have significant environmental impacts, leading to environmental degradation, pollution, and climate change. These environmental issues can in turn influence international relations, as countries seek to address common challenges through cooperation or face conflicts over environmental resources.

The following types of natural resources were identified in terms of their geopolitical importance in international relations:

  • Energy Resources
    • Oil and Gas: Countries rich in these resources hold significant geopolitical influence because of their control over global energy supplies.
    • Renewable Energy: The rise of renewable energy such as solar and wind energy is introducing a shift in geopolitical dynamics, in that more countries are investing in renewable technologies to lessen dependence on fossil fuels and to enhance energy security.
  • Minerals and Metals
    • Rare Earth Elements: These are essential elements for electronics and high-tech industries, and those countries who hold a dominant position in production have more geopolitical influence.
    • Precious Metals: Metals such as gold, silver, and platinum hold significance because of their value and perceived stability.
  • Water Resources
    • Freshwater: Access to this is essential for agriculture, industry and human survival hence, disputes over water resources often lead to tensions and conflicts among nations.
  • Agricultural Resources
    • Food Security: Countries with abundant agricultural resources may use this as leverage when it comes to trade and diplomatic negotiations.
  • Forests and Timber
    • Biodiversity: This holds ecological value which may economically benefit countries.
  • Fisheries
    • Marine Resources: Access to marine resources, such as fish stocks, can be a source of contention between countries, leading to disputes over fishing rights and maritime boundaries.

Locally, the Chamber of Mines of the Philippines has observed that heightened geopolitical risks typically drive up gold prices with investors seeking safe-haven assets.  As the Philippines is a major producer of gold, copper and nickel, commodities that are sensitive to both global demands and logistical challenges, the current situation is both an opportunity and a crisis due to the risks brought by global inflation, rising energy costs and potential delays in project execution.

According to the Chamber’s Chairman and President, Michael Toledo, “Despite global uncertainty, we remain cautiously optimistic about the resilience of the Philippine mining industry, particularly in gold, copper, and nickel production.” 

He added: “Elevated commodity prices, if sustained, present an opportunity to enhance national economic stability through increased revenues, job creation, and fiscal contributions.”

Geopolitical competition, particularly between China and the United States, has heightened the strategic value of Philippine mining.  China has long been a major investor in the country’s mining sector, seeking to secure supplies for its manufacturing-heavy economy.

In contrast, the US and its allies are increasingly pursuing "friendshoring" strategies to reduce reliance on Chinese-controlled supply chains, viewing Philippine minerals as a potential alternative source.

As global powers reposition for access to strategic resources, the Philippines finds itself at the nexus of economic opportunity and geopolitical tension. How it manages its mining sector could significantly influence both regional dynamics and its own path to sustainable development.

July 08, 2025

The reassertion of the "America First" policy under the renewed Trump administration in 2025 has reshaped global trade, energy, and strategic relations. At the heart of this shift is a clear prioritization of US economic sovereignty, energy independence, and critical mineral security. Under Trump 2.0, this approach prioritizes fossil fuel expansion, domestic mineral security, and skepticism toward multilateralism—pressuring allies to align more closely with US interests.

In particular, the US is doubling down on fossil fuel production and restricting support for renewable energy initiatives—rolling back incentives, freezing federal land leases for green energy, and canceling clean energy grants. At the same time, it is aggressively pursuing secure and “friendly” supply chains for critical minerals, incentivizing companies to source from allies like the Philippines.

Trump's policies challenge international cooperation through trade barriers and environmental deregulation. Global frameworks like the Paris Agreement and World Trade Organization have been sidelined, leaving developing countries like the Philippines exposed to policy vacuums. Trump’s approach often sidelines global institutions like the WTO and regional trade blocs.

These changes carry profound implications for developing nations, especially the Philippines, a country rich in nickel, copper, and other strategic resources. As a long-time US ally and a significant Chinese trade partner, the Philippines now finds itself delicately balancing economic opportunity and geopolitical alignment.

A Strategic Resource Battleground

Central to the Trump administration’s “America First” economic and national security strategy is the reduction of US dependence on foreign sources—particularly China—for critical minerals. These materials, including nickel, lithium, cobalt, and rare earth elements, are essential to high-tech manufacturing, electric vehicles, renewable energy systems, and defense equipment. The Trump administration has ramped up efforts to bolster US domestic exploration and mining and forge bilateral agreements with friendly nations for resource access.

While the US has limited reserves of certain minerals, it is using its diplomatic and economic influence to reconfigure the global flow of critical materials. Strategic partnerships and investments are increasingly directed toward countries seen as stable and aligned with US geopolitical interests. Export restrictions and trade barriers targeting Chinese-sourced materials are encouraging companies to seek new suppliers in Southeast Asia, Latin America, and Africa.

In particular, the Philippines, rich in mineral resources and situated in a geopolitically pivotal zone, finds itself at the intersection of shifting US trade, energy, and security policies. For the mining sector, the heightened demand by the US for critical minerals — especially nickel, copper, and cobalt — has elevated the Philippines’ profile as a potential strategic partner and alternative source for those commodities. American and Western-aligned companies have begun reassessing the Philippines as an investment destination. There is rising interest in investing in downstream facilities—such as mineral processing plants or battery component manufacturing—which the Philippines currently lacks at scale.

Energy Security in a Divided World

In the energy sector, the Trump administration’s renewed emphasis on fossil fuel dominance and skepticism toward international climate accords may undermine the Philippines’ transition toward renewable energy. US firms may promote liquefied natural gas projects or coal-based energy partnerships over green alternatives. Simultaneously, waning US leadership in climate diplomacy could stall global funding and technology transfers that are vital for developing countries to adopt clean energy solutions.

The Philippines' reliance on imported fossil fuels makes it vulnerable to global market fluctuations. As a nation with ambitious renewable energy targets—aiming for 35% renewable energy in its power mix by 2030 and 50% by 2040—the Philippines faces challenges due to these US policy shifts. A global resurgence in fossil fuel dependency could exacerbate energy security issues and hinder efforts to transition to more sustainable energy sources. The Philippines may see funding and interest in renewable projects decline, reinforcing reliance on LNG and coal.

The US withdrawal from global climate commitments and reduction in renewable energy funding may also lead to decreased international support for the Philippines' clean energy initiatives, potentially slowing down the development of solar, wind, and other clean energy infrastructures. The Philippine renewable energy sector has historically relied on foreign investments, technology transfers, and development aid—much of which has been bolstered by US leadership in climate finance. With US institutions (e.g., the Export-Import Bank, US Agency for International Development or International Development Finance Corporation) potentially deprioritizing green energy, major projects may face delays or cancellation.

Geopolitical Tensions and Maneuvering

Southeast Asia sits astride critical sea lanes, such as the South China Sea, through which one-third of global trade passes. The region’s proximity to Taiwan, its access to maritime resources, and its growing markets make it strategically vital. China asserts expansive claims in the South China Sea, backed by military installations and aggressive patrols. On the other hand, the US continues freedom of navigation operations and military exercises.

China’s growing military footprint in the South China Sea directly challenges Philippine territorial claims. In response, the US has strengthened defense ties with treaty allies like the Philippines and expanded access to bases under the Enhanced Defense Cooperation Agreement. The Philippines' proximity to key sea lanes and Taiwan makes it a military asset. However, over-reliance on US defense might provoke Chinese economic retaliation. As a strategic ally, the Philippines may receive increased military and economic support from the US However, this could pressure the Philippines to choose sides in the US-China rivalry, complicating its domestic policy on natural resource administration, environmental safeguards, and foreign investments. As geopolitical tensions deepen, the Philippines must navigate an increasingly polarized world.

Strategic Moves by Philippine Regulators

Philippines resources regulators—particularly those overseeing energy and strategic minerals—must move decisively to take advantage of emerging geopolitical and economic opportunities. Policy makers must seek inclusion in US strategic minerals initiatives. The government can also create a bilateral working group on resource security, linking the Philippine Department of Energy, Department of Environment and Natural Resources/Mines and Geosciences Bureau with the US Departments of Energy, State, and Commerce.

Trump’s hardline stance on China can also be used by the government to negotiate better terms with both US and China, especially in downstream mineral processing and energy infrastructure investments (e.g., grid development, offshore wind). To fast-track resource policy and institutional reforms, the government should also enact a National Critical Minerals Policy and a Philippine Mineral Security Strategy, which will set a development roadmap and look into offering fiscal and regulatory incentives for investments in critical minerals. Finally, the government should strengthen the nationwide geological survey, mineral, and energy data transparency, and ESG monitoring capacity to meet international compliance and due diligence standards.
 

Establishing a Philippine Department of Mines and Energy can be another strategic move. Currently, mining and energy are under the DENR and DOE respectively, leading to jurisdictional overlaps, especially in environmental vs. economic goals. A dedicated department could align policies, licensing, and enforcement under one roof, improving bureaucratic efficiency. Creating a dedicated department would also send a strong signal to international investors that the government is serious about developing the sector and ensuring stable governance. The unified department could integrate mining, mineral processing, energy production, and even green industrial development, creating synergies across sectors.

There is a risk, however, that creating a new department could lead to bureaucratic duplication or weak oversight, especially if it lacks experienced technical bureaucrats or a clear mandate. Setting up a new department requires legislative action, funding, and strong executive leadership. A premature launch could result in tokenism rather than transformation and the timing would depend on both the urgency of national priorities and the readiness of institutions.

The Philippines should move toward creating a Department of Mines and Energy—but only if a clear national mining and energy roadmap is in place and institutional capacity-building programs are underway with legislative and executive backing with adequate funding. If those conditions are not yet met, a transition phase—such as creating an inter-agency commission or task force—might be a better near-term step.

Political Realignment and Policy Implications

The 2025 elections resulted in the fracturing of the once-unified "UniTeam" alliance between President Ferdinand Marcos Jr. and Vice President Sara Duterte, into opposing factions. The resources industry stands at a crossroads with the new political configuration influencing its trajectory. The retention of key economic officials suggests a degree of policy continuity, which may reassure investors in the resources sector. In response to the electoral outcomes, President Marcos also initiated a cabinet reshuffle.

Notably, Raphael Lotilla transitioned from Secretary of Energy to Secretary of Environment and Natural Resources. The appointment of Lotilla has elicited a spectrum of reactions, reflecting both optimism and concern. Lotilla, who was my professor at the University of the Philippines College of Law, brings a wealth of experience from his previous government roles, including serving as Secretary of Energy under President Gloria Macapagal Arroyo, as well as holding a position in the National Economic and Development Authority. His involvement in the Electric Power Industry Reform Act of 2001 underscores his deep understanding of the energy sector and public policy.

However, environmental organizations have voiced concerns over Lotilla's past support for fossil fuels and nuclear energy during his tenure at the DOE. They urge him to shift towards more sustainable and climate-resilient policies in his new DENR role. Lotilla's previous affiliations with energy companies have also raised questions about potential conflicts of interest, especially given the DENR's role in regulating environmental compliance for energy projects.

Lotilla is walking on a tightrope. While his reputation for integrity and policy expertise is an asset, administering the DENR requires deep political acumen, grassroots coordination, and internal institutional reform—not just technical know-how. Success will depend on his ability to streamline decision-making and accountability across the bureaucracy, forge genuine consensus among competing interests, and professionalize DENR operations without getting mired in political interference. There’s constant tension between the push for resource exploitation (to drive economic growth and foreign investment) and obligations under environmental laws, climate goals, and protected area frameworks. Lotilla's ability to balance economic development with environmental protection will be pivotal. Stakeholders will be closely monitoring his policies and actions to ensure they align with the country's environmental and sustainability goals.

Meanwhile, the Supreme Court's recent decision to nullify local government units' (LGUs) blanket bans on mining activities—specifically overturning Mindoro Occidental's 25-year moratorium—has significant implications for the industry. The Supreme Court ruled that while LGUs have the authority to evaluate and approve or deny individual mining applications, they cannot impose blanket bans on mining activities. This decision reinforces the primacy of national laws, particularly the Philippine Mining Act of 1995, over local ordinances in regulating mineral resource development. The decision is seen as a step toward harmonizing local and national policies, thereby fostering a more conducive environment for sustainable mining operations.

The ruling is expected to boost investor confidence by providing a more predictable legal framework for mining operations. LGUs retain the power to assess and decide on individual mining projects, ensuring that local concerns and environmental considerations are addressed on a case-by-case basis. The decision underscores the need for coherent policies between national and local governments to balance economic development with environmental stewardship. The Supreme Court's decision delineates the boundaries of local and national authority in mining regulation, aiming to create a more stable environment for investment while still preserving the role of LGUs in environmental oversight. The long-term impact will depend on how effectively national and local policies are harmonized to promote sustainable and responsible mining practices.

Conclusion

Trump 2.0's return signals a renewed opportunity for the Philippines to strengthen bilateral ties with the US around critical minerals, energy security, and resource independence. Philippine regulators must proactively craft policy and commercial frameworks that de-risk investments in resources, accelerate project implementation, and align with evolving national strategic priorities. In addition, they must act decisively to align the country’s regulatory, diplomatic, and industrial strategies with the geopolitical reorientation of a second Trump presidency. Proactivity, policy readiness, and credible regulatory reforms will be essential to securing our place in the future of US-led critical mineral and energy supply chains. Finally, the Philippines must engage global powers with strategic confidence—welcoming investments and cooperation, but on terms that align with national development, uphold environmental integrity, and preserve its sovereign decision-making.


Fernando “Ronnie” S. Penarroyo specializes in Energy and Resources Law, Project Finance and Business Development. He is also currently the Chair of the Professional Regulatory Board of Geology, the government agency mandated under law to regulate and develop the geology profession. For any matters or inquiries in relation to the Philippine resources industry and suggested topics for commentaries, he may be contacted at fspenarroyo@penpalaw.com. Atty. Penarroyo’s commentaries are also archived at his professional blogsite at www.penarroyo.com
April 07, 2025

(Conclusion) 

By Noel B. Lazaro, Eveart Grace P. Claro, Judd Yonder L. Reyes, and Marielle D. Marbella

The global push for sustainability has reached a tipping point, compelling industries to accelerate their decarbonization efforts. Nowhere is this more critical than in mining—a sector paradoxically essential for the green transition yet burdened by its environmental footprint.

The first part of this article (see Issue 4 2024 – Editor) examined the Philippine mining sector’s decarbonization landscape, highlighting the challenges of attracting carbon project investments, the role of policy reforms, and the industry's response to emerging sustainability standards like Towards Sustainable Mining (TSM). It also explored legislative efforts, such as the Low Carbon Economy Investment Act and the Carbon Rights Act, to incentivize emissions reduction and integrate carbon markets.

This second part delves into the tangible steps mining companies must take to decarbonize, the barriers hindering progress, and the opportunities that could turn sustainability into a competitive advantage.

Metrics for Mother Earth

Sustainability reporting has become essential for businesses, particularly in mining. Since 2019, the Philippine SEC has mandated all listed companies to disclose their sustainability practices, achieving over 90% compliance. In 2023, the SEC reinforced this mandate with enhanced standards, including structured forms beyond narrative reporting to ensure thorough ESG disclosures.

An encouraging development is the SEC's move towards mandatory reporting, aiming to extend these regulations to unlisted firms.

Also, the Philippine Financial and Sustainability Reporting Standards Council (FSRSC) is introducing new reporting requirements for publicly listed extractive companies, mandating compliance with the International Financial Reporting Standards (IFRS) S1 and S2 by 2027. Developed by the IFRS Foundation's ISSB, these standards create a global framework for sustainability reporting, focusing on climate-related and financial issues that impact company value. IFRS S1 addresses general sustainability disclosures, while IFRS S2 targets climate-related disclosures, aiding companies in reporting how sustainability factors influence their long-term success and risk management.

The introduction of IFRS S1 and S2 significantly boosts board accountability in industries with major environmental impacts, particularly in addressing sustainability and climate-related issues. These standards mandate oversight of sustainability practices, measurable emissions reduction targets, and stakeholder transparency, positioning boards as environmental stewards. Non-compliance can impair asset values, reduce earnings, and erode investor trust.

With such standards, mining companies are set to establish trust among their stakeholders, thus attracting more investments with the promise of sustainability.

Gospel of Circular Living

The concept of a circular economy is fundamentally aligned with the principles of sustainability, focusing on reducing waste, maximizing resource efficiency, and promoting environmental regeneration. Unlike the traditional linear economy, which follows a "take-make-dispose" model, the circular economy emphasizes a closed-loop system where materials are reused, repaired, refurbished, and recycled to create a more sustainable, restorative system.

Viewing mining through the lens of the papal encyclical Laudato Si reveals the tension between humanity's resource needs and the moral duty to protect the planet. At a Vatican meeting on “Mining for the Common Good,” Pope Francis voiced concerns about profit-driven economic models that overlook environmental and human impacts. He advocated for a "circular economy" in mining, emphasizing resource reuse and waste reduction.

Circularity is essential in mining operations. Philippine mining companies must submit an annual environmental protection and enhancement program detailing measures to minimize extraction's adverse effects, including waste and tailings reduction, efficient water management, riverbank stabilization, progressive mine rehabilitation, and recycling of materials like tires and non-biodegradables.

The DENR complements the shift to a circular economy and low-carbon energy system through the Green Economy Program of the Philippines (GEPP). This initiative emphasizes integrated waste management and green technology. The GEPP aims to involve all government levels and private sectors in policy formulation and energy efficiency promotion.

Rohitesh Dhawan, CEO and President of the International Council on Mining and Metals (ICMM), describes how circularity can be made more impactful in an October 2024 report: “To achieve a circular economy at scale, innovative solutions are needed for both process and product.”

Treasure in Transition

The imperative to transition to a greener future embodies a paradox. The human activities driving carbon emissions are simultaneously vital for sustaining electrification, creating a delicate equilibrium between often opposing societal forces.

Consider the Tesla Model 3 that has a 50-82 kWh lithium-ion battery, using 2170 Nickel-Cobalt-Aluminum (NCA) batteries before 2023, and 2710 Nickel-Cobalt-Magnesium (NCM) batteries in vehicles manufactured in China and Berlin. Recently, Tesla adopted Lithium-Iron-Phosphate (LFP) batteries for the standard Model 3 (2021-2023). This highlights a critical issue: EVs rely on batteries, which require minerals, and minerals necessitate mining. This theme is central to Ernest Scheyder’s recent book, “The War Below: Lithium, Copper, and the Global Battle to Power Our Lives,” which examines the conflicts arising from the demand for essential metals.

Scheyder illustrates the complex interplay involving mining companies seeking to extract metals for value and revenue, residents opposing mine construction but seeking job security, environmentalists who acknowledge mining for the green revolution while striving to protect ecosystems, and regulators navigating both socio-economic interests and governance rules.

Identifying barriers to decarbonization in mining is crucial, particularly economic dependence. This reliance can foster resistance to decarbonization due to fears of job losses and economic decline. Transitioning from fossil fuels requires substantial investment, limited financing options, and community support, posing political and social challenges. Infrastructure limitations complicate matters. Effective decarbonization demands modern infrastructure, including reliable energy sources and efficient transportation networks. In many regions, inadequate infrastructure hampers energy project implementation and cleaner technology adoption, leading to stalled initiatives or increased costs. Technical challenges also arise in scaling up new technologies, which often require trailblazing research and development. This technological gap hinders the adoption of practices that could reduce carbon footprints. According to the Rockefeller Foundation, the Philippines needs approximately $9 billion to bolster renewable energy efforts, a figure that could rise to $165 billion by 2050.

The regulatory framework is another critical factor. Inconsistent or weak regulations and bureaucratic gridlock can lead to slow development. Absent fair and firm guidelines, companies may prioritize short-term profits over long-term environmental responsibility, thereby stalling progress in reducing carbon emissions.

Global market pressures can also impact the mining sector’s decarbonization efforts. Fluctuating commodity prices may deter companies from investing in sustainability initiatives.

Furthermore, supply chain emissions present another layer of complexity, as controlling emissions from suppliers and transportation can complicate overall decarbonization strategies. Awareness and education play a vital role in this context. A lack of understanding about the benefits and importance of decarbonization among stakeholders can hinder progress.

Despite these challenges, there are opportunities conducive to decarbonization within the mining industry. Electrifying operations by transitioning to EVs and equipment can lower emissions, particularly when powered by renewable sources. BloombergNEF’s 2023 report noted that lithium-ion battery costs have dropped dramatically during the previous ten years, reaching a record low of $139/kWh last year, due to increased production capacity and falling raw material costs. By 2030, advancements like solid-state electrolytes and anodes are expected to lower costs to $80/kWh.

The Philippines, rich in valuable metals like nickel, copper, and gold, has a combined value of $0.4 to $1 trillion. With adequate government support and a robust platform, it could position itself as an EV hub to rival Southeast Asia’s first battery plant in Indonesia.

On the other hand, integrating renewable energy sources, such as solar, wind, and hydropower, can significantly reduce reliance on fossil fuels.

For example, in 2018, Ipilan Nickel Corporation (INC) established a mini-hydro power plant with a 6-kW capacity to provide free electricity to the Indigenous community in Sitio Mararag, Barangay Maasin, Palawan. Since 2019, this facility has continuously supplied 220 volts to at least 32 households, including the Mararag Day Care Center. In 2022, the company also installed solar-powered lamp posts and plans to expand its solar initiatives, further supporting a cleaner environment.

Moreover, INC has initiated a 25-hectare mangrove plantation in the brackish waters of Española, Palawan, contributing to coastal protection and environmental restoration. If replicated across regions and industries, these efforts could be pivotal.

In compliance with DENR Administrative Order No. 2018-19, which sets strict limits on land disturbance and mandates immediate replanting or rehabilitation, mining companies are expected to implement comprehensive rehabilitation and reforestation efforts that not only restore biodiversity but also absorb CO₂. This can be strengthened by adopting circular economy practices that minimize waste.

Carbon pricing is another avenue worth pursuing. By creating a market for carbon credits, companies can receive financial incentives to lower emissions, encouraging innovation and cost-effective carbon footprint reduction strategies.

Governments are increasingly offering regulatory incentives to companies investing in green technologies, which could handsomely reduce costs—a strategy the Philippines should consider seriously.

Finally, stakeholder pressure is rising, with investors and consumers demanding more sustainable practices and driving companies toward adopting decarbonization strategies.

Balancing these opportunities and challenges will be crucial for the mining industry as it navigates the path toward effective decarbonization.

Min(e)d Your Business

A collaborative and multifaceted approach is required to overcome the barriers to a low-carbon future in the mining sector. Stakeholders can harness a culture of stewardship from initiatives like the DENR's green transition, clear and efficient regulatory policies, tax and financial incentives, international standards like the TSM model, meaningful sustainability disclosures, investment in renewable energy and carbon rights, upscaling circular economy practices, and access to research and technology.

Achieving net-zero emissions by 2050 may seem like a piper’s dream, but with every ambition turned into action, decarbonization can come within reach. The world watches—with bated breath.


Atty. Noel B. Lazaro, Atty. Eveart Grace Pomarin-Claro, Judd Yonder L. Reyes, and Marielle Marbella are key members of the Legal and Regulatory Affairs Group at Global Ferronickel Holdings, Inc. (FNI).

They were honored with the In-House Legal Team of the Year 2024 Best Practice Management Award (Corporate Social Responsibility) and were shortlisted for In-House Legal Team of the Year 2024 in the Energy and Natural Resources category by the In-House Community (IHC). The IHC represents over 21,000 in-house legal professionals across Asia and the Middle East and received a record 206 nominations in 2024 across 14 jurisdictions.

They were also celebrated at the Asian Legal Business (ALB)–Philippine Law Awards 2024, organized by Thomson Reuters, where they received the In-House Team of the Year 2024 (Construction and Real Estate) award and were finalists in the Philippine In-House Team of the Year 2024 and In-House Team of the Year 2024 (Innovation) categories. Atty. Lazaro was named among the Top 5 Philippine In-House Lawyers of the Year 2024.
March 18, 2025

At least once a year, when International Women’s Month is celebrated in March, we are reminded to pause and take stock of the role of women in resources development.

The mining industry in the Philippines, like many other countries, has traditionally been male-dominated.  Nevertheless, there are marked efforts to increase women's participation and address their unique challenges, thanks in no small part to the leadership of a woman Secretary of Environment and Natural Resources and to groups that are pushing this agenda.

Among the major issues faced by women in mining are: (1) gender division of labor, where women are confined to jobs that are less technical or less physically taxing; (2) limited access to education and training, which in turn limits their opportunities for advancement; (3) cultural and social barriers, which include cultural beliefs that prevent women from going underground; and (4) negative environmental and social impacts of mining operations.

To address these challenges, a number of steps have been identified:

1) Policy reforms. These include amending the Philippine Mining Act to include gender-sensitive provisions to ensure more equitable participation and opportunities for women.  Mining companies could also be mandated to conduct periodic gender impact assessments and sex-disaggregated data collection.

These reforms would also include a better implementation of the Magna Carta of Women in the mining industry and introducing guidelines, particularly for Social Development and Management Programs (SDMPs) which would encourage gender-responsive projects to meet the needs of women in mining communities. 

In this regard, Department of Environment and Natural Resources (DENR) Secretary Maria Antonia Yulo Loyzaga recently signed a new department administrative order mandating mining companies to incorporate the United Nations’ 17 Sustainable Development Goals (UN SDGs) into their SDMPs. Mining contractors and permit holders will have the responsibility of ensuring that SDGs are achieved within their host and neighboring communities.

The 17-point UN SDGs include, among others, no poverty; zero hunger; good health and well-being; quality education; gender equality, clean water and sanitation; affordable and clean energy; decent work and economic growth; reduced inequalities; and sustainable cities and communities.

2) Education and Training. This involves iincreasing access to education and training programs tailored to women to bridge the gap in technical skills.  Women often have limited access to STEM education which is essential for careers in mining. 

Mining companies can take the lead in developing and implementing training programs specifically for women in mining to hone their technical and management skills, and leadership.

There are existing programs, such as the United Nations Development Programme’s course on Gender and Mining Governance, which includes modules on promoting women's engagement in mining projects.

3) Empowerment and Leadership Opportunities. In a 2023 speech at the 10th anniversary celebration of Diwata – Women in Resource Development, DENR Secretary Loyzaga urged mining companies to empower women to lead and provide a platform that can harness their unique perspectives, knowledge and skills. “Mining companies are urged to enhance women participation in their conservation and restoration projects, acknowledging the indigenous women’s and other women’s invaluable knowledge of local ecosystems. The mining industry can mainstream gender-responsive policies in their corporate strategies, not only to ensure that practices do not inadvertently harm women, but that they also build corporate resilience,” Loyzaga said.

As this is being written, the Chamber of Mines of the Philippines (COMP), in partnership with PH-EITI and the Mines and Geosciences Bureau, has announced a forum entitled “Mining Her Own Business: Elevating Women’s Voices in Natural Resource Governance” which is expected to gather industry leaders, policymakers, academics, and development partners to discuss gender-responsive governance in the extractive sector.  The discussions will focus on:

  • Women’s participation in decision-making
  • Gender-sensitive data disclosures
  • The impact of mining revenues on women and marginalized groups

Although women continue to face significant challenges in the mining industry in the Philippines, there are concerted efforts to address these issues and create a more inclusive sector.  It is envisioned that, by promoting gender equality and providing opportunities for women to participate fully, the mining industry will become more sustainable and equitable for all stakeholders.

November 16, 2024

The recent October monthly meeting of the Philippine Mining and Exploration Association (PMEA) was filled to capacity as industry players eagerly awaited the keynote of newly appointed Department of Environment and Natural Resources (DENR) Assistant Secretary (ASec.) for Mining Concerns and concurrent OIC Director of the Mines & Geosciences Bureau (MGB) Michael Cabalda.

In his prepared speech, ASec. Cabalda highlighted a number of initiatives including: (1) pushing a proposed Department Administrative (DAO) order articulating a policy framework that would allow the country to gain from our mineral wealth; (2) streamlining the permitting process to reduce the time to 11 months or shorter; and (3) reviewing the Small Scale Mining Act to formalize small scale miners and increase their contributions.  These initiatives envision a mining industry that is not only an ore supplier but a critical player in mineral processing and downstream manufacturing.

The more spirited portion of the program was the Q&A where it was apparent that the audience was keen to hear directly from Assistant Secretary Cabalda in his first engagement with industry since his appointment.

Asked how soon the MGB will be able to implement the above policy changes, particularly the reduction of the processing period for permits, Assistant Secretary Cabalda credited DENR Secretary Maria Antonia Yulo Loyzaga for leading these initiatives, foremost of which is giving the MGB Director the authority to sign documents that previously needed to be cleared.  He also spoke about a more active MGB with respect to the pricing of nickel, statistics on safety and environment, among others.

Most encouraging was his assurance “Help me out and I’ll try to deliver and give you what you need.”  He added that the “MGB is your partner.  We will be with you when you do your work.”  His warning “and we will punish you when you don’t” drew laughter from the crowd.

A recurring theme was the need for communication between the government and the private sector and institutionalizing a mechanism for government to address problems raised by industry.  A suggestion to hold regular dialogs with industry was well received.

In addition, Asec. Cabalda expressed the need to touch base with his ‘council of elders’ or the MGB old-timers who possess the institutional knowledge and experience to be applied to (not-so-new) issues.  This is expected to promote consistency in the MGB’s interpretation and application of issuances across the different regional offices.  He likewise reiterated that he intends to build on what MGB, and the regional directors have done.

Another key strategy is to digitize all records and information to eliminate the current antiquated paper-based system.  With information being available online and available in real time, there will be greater transparency, as well as identification of where the bottlenecks are.

As Asec. Cabalda discussed the need for coordination with other government agencies, particularly the National Commission on Indigenous Peoples and the Department of Interior and Local Government, I recalled his comments (prior to his appointment) during the May 2024 “Mining Summit” where he said that there is no need to reinvent the wheel as there is an existing and comprehensive Minerals Action Plan prepared by the Minerals Development Council back in 2004, with specific and detailed items to address the identified challenges. Even 19 years later, it is replete with implementable action items.

It bodes well that our new MGB Director is approaching his role with openness and candor.  The industry can do no less by responding in kind.

***

Postscript: Due to family commitments, I missed the Chamber of Mines’ “Digging Deeper” Policy Forum and will also miss, for the first time in recent years, PMSEA’s Annual National Mine Safety and Environment Conference (ANMSEC). 

The ANMSEC has always been an opportunity for Diwata-Women in Resource Development to contribute to the discussion of important mining issues, as well inviting the participation of the ambassadors of countries which are developed mining jurisdictions.

One particularly memorable event for me was our 2012 forum featuring the Deputy Mineral Resources Minister of South Africa, Godfrey Oliphant.  He was a fiery and outspoken advocate for mining, despite his once being a member of South Africa’s Communist Party.  His story of how he came to realize the important role that mining played in South Africa’s economy was the perfect counterpoint to the student activists who had met him in UP Baguio.

November 16, 2024

(Part One of Two)

Written by Noel B. Lazaro, Eveart Grace P. Claro, Judd Yonder L. Reyes, and Marielle D. Marbella

In the foothills of Brooke’s Point, Palawan, the air is thick with purpose as workers press seedlings into the earth, each one a small promise for a greener future. Two years into its operation, the Ipilan Nickel Project has planted nearly three million seedlings. Yet, while the commitment to reforestation is clear, the challenge lies not in the availability of seedlings or the manpower to plant them, but in securing suitable land for these young trees to thrive within the municipality’s 85,064.90 hectares. Afforestation of previously scorched mountainsides and agroforestry initiatives are underway.

By May 2024, mining companies had planted over 55 million seedlings in more than 50,000 mined-out areas, expecting a survival rate near 90 percent. Tree planting can help local communities, but it is not a complete answer.

Mining drives the world’s economy, providing raw materials vital for industries. The World Economic Forum notes that half of global GDP relies on natural resources. But mining comes with heavy costs. A 2020 McKinsey report estimates that mining produces 1.9 to 5.1 gigatons of carbon emissions yearly, largely from coal-bed methane and energy use. In 2022, the Deloitte Economics Institute warned that climate change could lead to global losses of $178 trillion from 2021 to 2070. In the Philippines, the Nationally Determined Contributions (NDC) indicates that the mineral industry will continue to be a major greenhouse gas (GHG) emitter through 2030.

This article examines the challenges and opportunities for decarbonization in the Philippine mining sector.

GREEN (EV)OLUTION

Decarbonization is essential for mitigating climate change by reducing or eliminating carbon dioxide (CO2) and other GHGs. It involves transitioning to cleaner energy sources and adopting sustainable practices to lower pollution. The ultimate goal is achieving "net-zero" emissions, where the amount of GHG released is balanced by the amount removed. Emission control can be achieved through natural methods like tree planting or watershed restoration, and the costlier technological solutions such as direct air capture and storage.

Source: Visual Capitalist (https://www.visualcapitalist.com/)


As the global community grapples with the urgent need for sustainable practices under the 2015 Paris Agreement, the Department of Environment and Natural Resources (DENR) has launched a "green transition" initiative. Secretary Maria Antonia Yulo-Loyzaga frames the transition as a “whole-of-society” effort, advocating for science and technology investments alongside social and ecological considerations. Her emphasis on promoting biodiversity, carbon footprint reduction, and effective waste management practices is a step in the right direction.

At the Nordic-Philippine Climate Executive Dialogue held on June 18, she advocated for “nature-based solutions” for carbon reduction, suggesting a preference for simpler, less costly strategies over more complex carbon capture technologies. However, nature-based solutions, while essential, must be part of a broader strategy that includes robust carbon and efficient regulatory frameworks and tech advancements to genuinely meet the country’s pledge to reduce GHG emissions by 75 percent by 2030.

The secretary highlighted the Philippine Ecosystem and Natural Capital Accounting System (PENCAS), which aims to quantify the value of natural resources, including minerals, to socio-economic development and includes addressing the impacts on ecosystems by adopting the mitigation hierarchy in mining operations, which follows the steps of avoidance, minimization, restoration, and offsetting compensation for affected communities. On the other hand, the DENR's recent release of the Implementing Rules and Regulations for the Extended Producer Responsibility Act of 2022, which mandates large companies to manage plastic waste, is a positive development.

The drive for modern infrastructure—encompassing electrification, renewable energy, automated systems, and AI-powered monitoring—represents a critical yet challenging evolution. In this context, electric vehicles (EVs) offer cleaner alternatives that reduce reliance on diesel machinery, which, according to a 2023 Mining Technology report, emits high levels of nitrogen oxides (NOx) and sulfur dioxide (SO₂). EVs are also safer and quieter, contributing to lower fire risks.

However, such transformations often require substantial investments that can be prohibitively high. Thus, the call for effective incentives is crucial, but details remain vague. For Atty. Dante R. Bravo, president of Global Ferronickel Holdings, Inc. (FNI) and Philippine Nickel Industry Association, Inc. (PNIA), the industry “needs clarity in terms of incentives for mineral processing” and “competitiveness given the size of investments required.”

The dialogue around margin-based royalties and windfall profit taxes is envisioned to help build a more equitable arrangement.

IN THE PIT OF CHANGE

The Chamber of Mines of the Philippines (COMP) has made a significant stride by launching the first phase of its Towards Sustainable Mining (TSM) initiative among its 19 members. This global standard for environmental, social, and governance (ESG) performance provides mining companies with essential tools to manage risks responsibly and adopt best practices. As the only ASEAN nation to adopt TSM, the Philippines sets a noteworthy precedent in the region.

The initiative focuses on vital areas such as health and safety, outreach to Indigenous Peoples, crisis management, tailings and water management, biodiversity conservation, and climate change. During the “Mining Philippines: Digging Deeper 2024” conference on October 17, four of eight randomly selected companies received the highest ratings across five key TSM protocols.

However, concerns remain regarding the scalability of these practices across the 56 large-scale metallic and 59 non-metallic mines, along with over 3,000 small quarries in operation. The voluntary nature of TSM and its reliance on self-assessment raise doubts about its effectiveness. Inconsistent adherence, particularly among non-members, could diminish the initiative’s overall impact.

This situation underscores the need for a more structured approach that transcends self-regulation. Regulators and legislators should take cues from TSM to develop a governance framework beyond existing mining laws and ISO benchmarks, potentially incorporating training and resource access.

TSM raises the compliance bar, but its success depends on overcoming limitations and fostering inclusivity.

CARBON CREDIT CARD

Investing in carbon rights is touted to be a more ingenious approach to offset carbon emissions. Generating a new source of income helps to meet financial objectives while also advancing global carbon reduction goals.

The proposed Low Carbon Economy Investment Act (House Bill 7705) aims to advance the Philippines' transition to a low-carbon economy. This legislation requires major GHG emitters to formulate decarbonization plans limiting global temperature increases to below 2°C. It also introduces a carbon pricing mechanism that imposes costs on emissions exceeding set thresholds, thereby creating a decarbonization fund. This fund is intended to be reinvested in sustainable, low-carbon initiatives, offering considerable opportunities for businesses and investors committed to sustainable development.

Concurrently, the Carbon Rights Act (House Bill 10635) is envisioned to overcome obstacles to investing in carbon forestry and related projects. This legislation clarifies ownership of carbon rights and establishes processes for their transfer, thus enabling better integration into global carbon markets. For investors, particularly those focused on nature-based solutions, this act opens new avenues for investment in essential carbon projects intended to achieve global emission reduction goals.

Carbon trading involves the exchange of emission rights and credits that permit organizations to emit specific volumes of CO2. Companies can purchase credits to increase emissions or sell them to reduce emissions. This system allows mining companies to support biodiversity and restore ecosystems while generating revenue.

Atty. Analiza Rebuelta-Teh, DENR Undersecretary for Finance, Information Systems and Climate Change, recently disclosed that the Department of Finance is creating a framework for carbon finance while the DENR is working on the rules for carbon credits.

These legislative initiatives signify notable progress, yet substantial challenges loom. The effectiveness of the Low Carbon Economy Investment Act hinges on precise baseline emissions data, rigorous enforcement, and vigilant monitoring; without these, companies may underreport emissions or sidestep decarbonization commitments. In addition, the viability of the carbon pricing mechanism depends on businesses' capacity to adapt, requiring time to develop essential infrastructure and mitigate oversupply issues that have plagued other markets. Public backing for carbon pricing presents difficulties, particularly if it results in higher consumer costs; thus, clear communication of its benefits is essential. Furthermore, while the Carbon Rights Act aims to attract investment into carbon projects, potential investors may confront legal ambiguities, bureaucratic hurdles, and a lack of transparency. Ultimately, the Philippines must compete with other nations for carbon project investments, necessitating demonstrable benefits, a stable regulatory framework, and proactive policies to avoid the pitfalls faced by early carbon markets in the European Union.

Addressing these hurdles will be crucial for their successful implementation and maximizing the benefits of a transition to sustainable practices.


(To be continued…)


Noel B. Lazaro is a director and general counsel at Global Ferronickel Holdings, Inc. His practice spans diverse fields, including environmental litigation. He was an associate at SyCip Salazar Hernandez & Gatmaitan and a partner at Siguion Reyna, Montecillo & Ongsiako. A UP College of Law graduate, he teaches evidence, special proceedings, and special writs at law schools.

Eveart Grace Pomarin-Claro is the Corporate Secretary of Global Ferronickel Holdings, Inc. and the Executive Legal Officer at Platinum Group Metals Corporation. A University of St. La Salle College of Law graduate, she specializes in securities and capital markets, taxation, project finance, and mergers and acquisitions.

Judd Yonder L. Reyes is a research associate and paralegal at Platinum Group Metals Corporation. A Bachelor of Arts in Communication graduate (Magna Cum Laude) from Pamantasan ng Lungsod ng Maynila, she completed the 29th Foundation Course of the Paralegal Training Program of the University of the Philippines - Law Center.

Marielle Marbella is a research associate and paralegal at Platinum Group Metals Corporation. A Bachelor of Science in Life Sciences-Communication Track graduate (Magna Cum Laude) from Ateneo de Manila University, she has a background in journalism and supports the group’s sustainability programs.

November 16, 2024

​

It has been almost four decades since I have worked in the resources and energy industry. My career history can be set against the backdrop of the ups and downs of the industry starting from the time I began working as a government petroleum geologist up to the present where I am both a government regulator and a private law practitioner.

I witnessed the paradigm shift in the industry when environmental protection became the norm in the 80s and indigenous peoples' rights were given legal recognition in the 90s. The millennium saw how green energy transition and digital transformation drove companies to adhere to the ESG framework extending sustainability beyond environmental issues to  encompass climate change, human rights, monitored revenues, and strict adherence to laws.

I embarked on a geology course upon the persuasion of my parents who wanted me to have a stable and relatively high-paying job. A relative was gainfully employed as a structural geologist in a government corporation and my parents believed that the profession offered numerous opportunities for career advancement.

So, there I was, a wide-eyed high school graduate from a small parochial school, enrolled in UP in a freshman block composed of 15 geology and 15 engineering majors. The group was a merry mix-up of kids from both exclusive and public schools, and uber-smart guys from Xavier School and Philippine Science High School who ate advanced calculus for breakfast. Our block president became active in university politics and was elected as University Student Council Chair, a prelude to his eventual rise as senator of the republic. Many in our freshmen block pursued their PhDs in geology while surprisingly, a good number became lawyers like me.

Amidst the political turbulence and economic chaos brought about by the assassination of Benigno “Ninoy” Aquino, I obtained my geology degree. Little did I realize that graduation from the university was just the beginning of the real challenge. Employment in the geoscience field depended highly on the price of commodities, particularly metals and oil. We entered the job market when metal and oil prices in the eighties were depressed. Qualifying for a geoscience job in the resources industry was difficult. The options were either being employed as a contractual worker in government or staying in the university as a research assistant while pursuing graduate studies. Private companies were not hiring and in fact retrenching their technical people.

In the 1970s, copper prices trended upward and peaked. The country’s copper production continued and boomed until 1980 when output recorded its highest production. Meanwhile, the 1973 energy crisis, also known as the Oil Shock of 1973–74, was a period of skyrocketing energy prices and fuel shortages resulting from an embargo by Arab oil-producing nations in response to U.S. support for Israel during the Yom Kippur War. These periods saw the initial boom and increase in demand for geologists.

However, in 1986, Saudi Arabia grew tired of attempts to stabilize the oil glut in the market by curbing its output and increasing oil production from two to five million barrels of crude oil per day. Between August 1985 and August 1986, crude oil prices plummeted from $28 per barrel to $8 per barrel before stabilizing at $18 per barrel.

During the oil price decline, copper prices also recorded low prices brought about a decline in demand for the metal. The world recession in 1982 – 1984 also pulled down copper prices further dampening demand, which fell more steeply than crude oil.

In the 1980s, the Philippine mining sector started its decline with the closure of several mining companies due to the financial crisis and the occurrence of several mining accidents. Inflation brought about by the debt moratorium crisis in 1983 and unstable political environment, devalued the Philippine peso effecting an increase in the costs of mining production, materials and equipment. Aggravating the situation were the economic crisis and political unrest in the Philippines in the mid-eighties. There were basically limited employment opportunities for new geology graduates at that time.

As a twenty-year-old and fresh from the university, I was practically forced to accept any technical job offered to me. My family was concerned that I would just be bumming around the house after graduation, so I accepted a job as a contractual cartographer at the Bureau of Energy Development (BED) under the then Ministry of Energy. Friends and classmates chided me as overqualified for the job and described my work as nothing but a glorified draftsman.

Beggars can’t be choosers because there were no permanent positions for new geology graduates who have not even hurdled the board examinations. Thankfully, BED management gave us, the new graduates, leeway to review for the board exams. The senior geologists also provided us with a collection of review materials and past examinations for our guidance. However, human resources cautioned us that we would lose our jobs if we fail the board exams. So, we used our allocated time in the afternoon to study and attended review classes in the evening.

In August of that year, a few months after graduating and getting employed in April, I took the board exams. After passing the licensure exams and becoming a registered geologist, I was regularized and became a permanent government employee with the title junior science research specialist.

Fortunately, when I entered the BED, there was an existing World Bank-funded project called “Petroleum Exploration Promotion Project”. The Project aimed to rekindle the interest of petroleum companies in exploring for oil and gas in the Philippines by undertaking a nationwide evaluation of the petroleum potential of the country’s fifteen (15) onshore and offshore sedimentary basins. Aeromagnetic and offshore seismic surveys were undertaken and the information generated was integrated with comprehensive regional basin evaluation studies. The more prospective Northwest Palawan and Reed (Recto) Bank areas in the West Philippine Sea were subsequently included in the study. Complementing the Project was a grant from Petro-Canada International Assistance Corporation, which acquired additional seismic data in selected offshore areas.

The Project also aimed to strengthen the exploration knowhow and technical capabilities of the government implementing entities - the BED and the Philippine National Oil Company Exploration Corporation (PNOC-EC). It was an effective mechanism of training the Filipino technical staff involved in the Project and I was a beneficiary of the knowledge transfer. My colleagues and I were mostly young geologists and geophysicists with very little exploration experience when we joined the BED.

It was in the Project where I initially learned the ropes of petroleum exploration. I was exposed to several aspects of exploration from seismic data acquisition, processing, and  interpretation when I was assigned to the geophysics section. It was an effective on the job training for me as I was under the supervision of World Bank foreign consultants and Filipino senior geoscience professionals seconded to the BED from PNOC-EC.

During the marine seismic survey conducted by Petro-Canada, I was sent aboard the research vessel to familiarize myself with the seismic data acquisition process. Marine data acquisition was conducted by using seismic vessels outfitted with sources and streamers that are towed behind the ship. I was seasick for the first few days and was advised to stay in the cabin. When I recovered from motion sickness, my job was to assist in the lay-out and design of the survey lines. I also helped in the quality control of the initial data generated.

It was a spectacular feeling of being out in the open sea. The rhythm of the waves and the wind can help clear the mind and make one feel more connected with nature. I also experienced the sight of so many marine life like dolphins, sharks, flying fish, box jellyfish, and sea birds.

The raw seismic data were then sent to the data processing center. The recorded seismic signals were analyzed to filter unwarranted noise to create an image of the subsurface and enable geological interpretation and identify structures for petroleum accumulation. Under the Project, PNOC-EC set up their own seismic processing center funded by their own loan from the World Bank. Part of my training as a geophysicist was my assignment to PNOC-EC’s Data Processing Center to understand how seismic data are prepared for analysis and interpretation. Seismic data were stored in magnetic tapes and once processed were printed on paper sections.

Seismic interpretation was the last stage in seismic exploration and used to infer the geology at certain depths from the ocean bottom. In the 1980s, data were first reproduced from sepia films using ammonia-based blue printing machines. Seismic interpretation was still done manually on paper sections of two-dimension data using colored pencils. At that time, we pressed our face sideways against the paper seismic sections spread across a long table. By looking sideways, we were able to trace subsurface horizons and large structural traps that could hold oil and gas deposits. We also encoded data and made structural contour maps manually without the aid of modern computer workstations and basin modeling software. The structural maps generated are then incorporated with other geoscience data to create drilling prospects. The exploration geologist would then have to convince higher management that the mapped prospects contained petroleum in commercial quantities.

In addition to mentoring us in the basics in seismic exploration, BED management also allowed us to attend short in-house advanced training courses organized by the World Bank. Foreign experts were engaged and flown to the Philippines to conduct these one-week training courses. The classroom seminars and workshops allowed us to fully understand the theoretical and analytical concepts behind petroleum exploration.

With the change of government after February 1986, and the marked improvement and stabilization of oil prices towards the end of the year, things began to pick up for the upstream petroleum industry. The results of the assessment of the petroleum prospects were assembled in the form of a promotional package contained in 70 sets of a 12-volume report which consisted of a project summary, six volumes of texts and appendices, four atlas volumes and one supplement. The promotion of the Project was finally implemented in 1987 with roadshows conducted by senior government energy officials in major cities in the world to entice foreign oil companies to explore in the Philippines.
 

Following the conclusion of the World Bank project, management decided to send me abroad to attend a graduate diploma course on petroleum exploration and production. I was sent to Europe for further technical studies at the Norwegian Institute of Technology located in the university city of Trondheim, north of Oslo. Norway is a major petroleum producing and exporting country tapping the vast marine wealth of the North Sea, one of the busiest but treacherous bodies of water. It has an international assistance program for developing countries like the Philippines, which funded the studies and training of young professionals in different technical fields.

Norway also boasts to have the world’s largest sovereign wealth fund, a government-run investment fund that invests in assets such as stocks, real estate, and bonds. The aim of the fund is to ensure a long-term management of revenue from its oil and gas resources, so that this wealth benefits both current and future generations. Investments are spread across most markets, countries, industries, and currencies to achieve a broad exposure to global growth and value creation and ensure good risk diversification.

Selected geologists from around the world were provided scholarships to study specialized subjects in petroleum exploration and production by the Norwegian aid agency. For ten months I was back at the university, imbibing highly technical subjects together with other international students. I studied with inquisitive mainland Chinese whose country was then starting to liberalize their economy and super competitive Indians who have to pass a battery of government examinations to win the scholarship. There were also other Asians, Africans, South Americans, and Europeans with different levels of experience.

A small Filipino community existed in Trondheim composed of nurses and their families, and Filipinas who were married to Norwegians. They took good care of Pinoy scholars, and certainly made life bearable in a far and cold country. At that time, the world was not that globalized yet and Norwegians in a small town have very limited encounters with Asians. Except for a few Vietnamese “boat people” refugees who sought political asylum in Norway from their communist government, Norwegians have but a few interactions with young, dark-haired East Asians like me. On several occasions inside the public bus and train, I noticed blonde, blue-eyed descendants of Norsemen staring and smiling at me. Perhaps my “exotic” looks back then were the precursor of the present K-pop phenomena. If you dare to ask me whether I have had a Scandinavian girlfriend, that is best left narrated in another article.

When I returned to the Philippines after my scholarship, it was the time when the Philippines began to reap the fruits of the success of the World Bank Project. During the late eighties to early nineties, the country was on the radar of large petroleum exploration companies like Exxon, Shell, British Petroleum, Chevron, Atlantic Richfield, Occidental, and other majors. The release of the Report coincided with the discovery of the Camago-Malampaya natural gas field by Occidental and Shell, and the start of oil production from the West Linapacan by Alcorn Petroleum.

It was a bullish era for the upstream petroleum industry. The BED now renamed as the Office of Energy Affairs, following the reorganization and downgrade of the Ministry of Energy by President Corazon Aquino, was busy managing petroleum service contracts and applications. It was then the opportune time to harness my newly acquired technical knowledge. But the irony in government service is that the moment one begins to climb the career ladder, more administrative work is assigned to the individual. In my case, I was charged with more compliance review work addressing the technical and financial qualifications of applicants for production sharing agreements and service contracts.

They say that if you want to see the world, then be a geologist. While there are certainly numerous opportunities for graduate studies and employment abroad for geologists, the profession also has inherent occupational and personal security risks. Field geologists often work in remote, harsh, and unpredictable environments, where they may encounter natural hazards, wildlife, accidents, or even violence. They explore frontier areas rampant in banditry, insurgency, and lawlessness.

My best friend in college who entered the BED with me at the same time, met a tragic accident off the waters of Tablas Island in Romblon province during fieldwork. He was a good swimmer, but he lost his young life trying to save another friend and colleague from drowning when their speedboat capsized in choppy waters. Both died in the accident, and it was such a terrible reminder to the office not to take safety precautions lightly. It was truly heart breaking on my part to inform his parents about his death. A sad day indeed when I was also tasked by the office to retrieve his remains from Romblon and bring him home through a chartered eight-seater plane arranged by the government.

Another blockmate from UP who has a PhD also perished in a helicopter crash together with a nationally renowned volcanologist while doing aerial survey work in the Sierra Madre for the Philippine Institute of Volcanology and Seismology. Geology is indeed a fascinating and rewarding field of study, but it also comes with many risks and challenges. Geologists also face pressures, such as long hours, deadlines, and numerous travel which take them away from their family and friends.

Why did I pursue a career in law?

(To be continued)


Fernando “Ronnie” S. Penarroyo specializes in Energy and Resources Law, Project Finance and Business Development. He is also currently the Chair of the Professional Regulatory Board og Geology, the government agency mandated under law to regulate and develop the geology profession. Atty. Penarroyo was recently awarded the 2024 Distinguished Alumnus Award for Geosciences by the UP Alumni Association. For any matters or inquiries in relation to the Philippine resources industry and suggested topics for commentaries, he may be contacted at fspenarroyo@penpalaw.com. Atty. Penarroyo’s commentaries are also archived at his professional blogsite at www.penarroyo.com


Reference:

The World Bank, Report No. 8891 “Project Completion Report: Philippines Petroleum Exploration Promotion Project (Loan 2201-PHL)”, 29 June 1990, https://documents1.worldbank.org/curated/en/422601468333040235/pdf/multi-page.pdf
​